A Sign Of The Times

A sign of the times that the Dubai economy is continuing to head in the right direction came from the Land Department which reported a 21% increase in H1 transactions to US$ 17.2 billion. With improved demand, especially for properties in certain areas, the market has stabilised and prices have begun to escalate. Of the 19,000 transactions recorded, mortgages accounted for US$ 8 billion or 47% of the total for the period. Overseas buyers generated US$ 7.7 billion of all the business.

Even Dubai Financial Market Company (PJSC) got in on the act by announcing a 140% increase in H1 Net Profit to US$ 11 million on Revenue of US$ 32.3 million. In addition, DFM trading value has rocketed from US$ 6 billion in H1 2011 to US$ 8.8 billion this period. (For the record, the Dubai Financial Market Index ended the week at 1572 up from the Sunday start of 1551).

A recent survey reported that business confidence in the non-oil sector moved marginally higher in June with the only hiccough being a contraction in export orders. This mirrors the current buoyancy in the local economy which has seen many of its indicators heading north whilst most of the world is going in the opposite direction.

Despite this plethora of positive news and the strong corporate results reported last week, Dubai Investments bucked the trend with a disappointing 54% fall in Q2 profits to just over US$ 17 million on Revenue of US$ 172 million (a fall of over 13% from almost US$ 200 million in Q2 2011). The company has assets of US$ 3.7 billion.

June saw a slight drop in the UAE money supply as the amount of local currency in circulation fell 1.3% to US$ 14.4 billion. However when this is added to monetary deposits of US$ 62.9 billion to give money supply aggregate M1 there has been a 1% increase to US$ 77.3 billion. Whilst bank deposits have decreased 1.6% to US$ 301 million, bank loans have risen1.5% to US$ 297 million and total bank assets have nudged upwards to US$ 471 million.

Indeed it seems that the value of remittances being sent home by expatriates is on the increase aided and abetted by  big recent devaluations in some of the currencies (including Pakistani rupee, Indian rupee, sterling, taka and euro). The World Bank estimates that remittances to developed countries will reach US$ 350 billion this year with India (US$ 58 billion), China (US$ 57 billion), Mexico (US$ 24 billion) and Philippines (US$ 23 billion) being the major beneficiaries. The GCC accounts for over 50% – or US$ 48 billion – of all remittances to South Asia and almost 30% – or US$ 36 billion – to the MENA region.

The GFC and the ensuing malaise here in Dubai are now distant memories as the emirate has sorted out its problems. This year, Dubai has about US$ 15 billion in debts maturing which will either be paid off or restructured. The yield on Dubai’s November 2014 Islamic bonds is currently hovering around the 3.25% mark which shows the market’s increasing belief in the emirate’s creditworthiness.

The opposite applies to the eurozone where confidence levels plummeted as the economy slid into deeper trouble and ever-worsening crisis. For example, Spain’s economy contracted for the third quarter in a row and will definitely require additional funds (a lot more than the US$ 120 billion being bandied about) from the European Central Bank.

The other basket cases are faring just as badly as Spain. Greece sees its credit rating dropping from stable to negative as its situation worsens with estimates that its economy next year will shrink a further 11%. The deepening crisis in Italy was highlighted by a Q2 0.7% contraction and a 2.5% year on year fall in its GDP. No wonder there is increasing concern in the markets that Italy will be going down the same road as Greece, Portugal and Spain, particularly since its debt burden represents 123% of GDP.

At the same time, France is expected to fall back into recession in Q2 when figures are announced and this contraction will continue for the rest of the year. More worryingly, Germany’s exports in June fell 1.5% and industrial output by 0.9% with further declines in the manufacturing and construction sectors. Germany is slowly being dragged under by its eurozone partners.

To further exacerbate the problem, the banking sector is bedevilled by a series of unwelcome drawbacks. The Libor scandal, which saw Barclays hit with a US$ 460 million fine, rumbles on with news that US bank, Berkshire, is suing 21 banks for damages over this alleged fraud. The London Interbank Offered Rate is fixed daily by the British Bankers’ Association and sets values on US$ 360 trillion of financial products. The fallout from this is bound to be massive and messy.

There is a good chance that Standard Chartered can join HSBC on the “Walk of Shame” as US regulators claim that the bank hid US$ 250 billion in transactions with Iranian banks. Although much larger than the US$ 16 billion that HSBC allegedly transacted, the modus operandi is similar – systematically disguising forex deals in contravention of US sanctions.

Another finance company in trouble is a leading market-maker on the NYSE. An IT problem last week saw US$ 440 million disappear from the books of Knight Capital. To save itself from going under, the company has had to agree to a US$ 400 million rescue deal with a group of Wall Street firms. Obviously a gold medal for gross ineptitude!

There is no doubt that the London Olympics have been a huge success but one has to question why such an event, that is supposedly promoting healthy living, lists McDonald’s and Coca Cola among its major sponsors.

On the subject of the Olympics, Jose Havelange, IOC member from 1963 – 2011 and former FIFA president , was named as a beneficiary of bribes from ISL, a company granted exclusive marketing and TV rights for the 2002 and 2006 FIFA World Cups. It was revealed that Havelange and his cohort and ex son-in-law, Ricardo Teixeira, received at least US$ 1.5 million and US$12.6 million respectively.

Unfortunately too many individuals are fiddling the system for their own personal greed, too many institutions – banks, media, government officials and politicians – are betraying the trust of their stakeholders and too many leaders are more concerned about their own welfare rather than the good of their country. Maybe it is just a sign of the times in which we live.

Posted in Finance | Tagged , , , , , , | Leave a comment

Should I Stay or Should I Go?

HH Sheikh Mohammed bin Rashid Al Maktoum started the week off well with a bullish speech about the state of the Dubai economy which appears to have gotten over its problems following the GFC. He contrasted the local economy with all the troubles emanating from the eurozone crisis, flagging global growth and other economic ailments affecting many other countries.

This confidence resonated around the emirate and the mood further improved  as many of the larger companies announced impressive Q2 results with Emaar, Nakheel, Du and Union Properties all coming in above analysts’ estimates.

The turnaround in the real estate sector is highlighted by the progress made by Emaar Properties and Nakheel. The former announced H1 revenue in excess of US$ 1 billion with net profit of US$ 332 million, being 45% higher than this time last year. Meanwhile Nakheel reported H1 revenue up a staggering 112% to US$ 850 million whilst there was a 36.5% increase in half yearly net profit to US$ 210 million.

Du’s Q2 revenue rose 13% to US$ 680 million whilst there was a 57% leap in net profit to nearly US$ 90 million. The company is catching up with its only other rival, Etisalat, and its 5.7 million mobile subscribers represent 46.5% of the total market.

Union Properties has seen a US$ 165 million turnaround in its fortunes from a US$ 142 million loss in Q2 2011 to a current quarterly profit of US$ 23 million. The market is obviously happy with the company’s recent progress as its shares are up over 45% this year.

Dubai Islamic Bank saw a 27% increase in its quarterly net profit to US$ 85 million with an H1 profit of over US$ 150 million. At 30 June, its total assets stood at US$ 25.5 billion with customers’ deposits at US$ 18.5 billion.

Even the Dubai International Financial Centre is getting in on the act announcing that, in 2011, its value of business reached over US$ 3.1 billion and the number of businesses operating increased to over 800. The outlook this year is for improved results and, having been responsible for 3% of Dubai’s growth and 1.4% of the UAE’s non-oil GDP in 2011, it hopes to add even more to the economy this year.

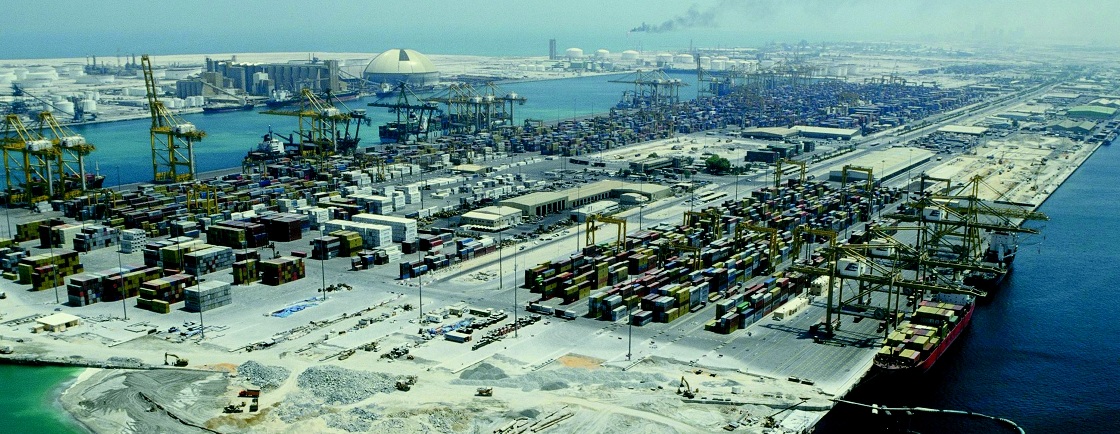
Finally and despite the global downturn, DP World bucked the trend by reporting a 7.5% increase (or 28.2 million TEUs – twenty foot equivalent units) in the volume of containers it handled in H1. The company, with sixty terminals globally, saw the largest growth (12%) in the Far East and the lowest (3.2%) in Europe. Its flagship base, Jebel Ali, handled 6.6 million TEUs – a 7.3% rise over the same period last year. No wonder that Dubai’s recovery was reflected in the latest figures showing a 13.3% rise in H1 exports and re-exports to US$ 37 billion.

Even the local bourse is getting in on the act with the DFM posting a weekly gain of 41 points ending at 1551 and almost 15% up since 01 January.

The feel good factor, resulting from these corporate financial results, was further enhanced by Dubai hotels recording June increases in profit. There was a 50% increase in gross operating profit per available room to US$ 86 and a 10% increase in revenue per available room to US$ 148. These impressive returns are expected to continue for the rest of the year. Interestingly a report on GCC completed construction projects expects that the hotel and hospitality sector will see their project values triple this year to US$ 7.3 billion!

The sector will receive an unexpected boost with Dubai hosting the XVII Annual World Investment Conference in September, being held for the first time in the MENEASA region. Over 500 attendees, representing 250 investment promotion agencies and from over 150 countries, will surely bring smiles to both the hospitality and retails sectors.

One country whose hospitality industry may be hurting (mainly from its ridiculously high exchange rate) is Australia but it may benefit in other areas from two UAE sources. The first was the signing of a nuclear cooperation agreement with a 15 year contract to supply uranium for the UAE’s new atomic power plant. The other news was that the loss-making Qantas Airways confirmed that it was in negotiations with Emirates Airline about a future alliance. No doubt a code sharing arrangement with the world’s largest long-haul carrier will add business and save costs for the world’s second oldest airline.

Emirates hub, Dubai International Airport, witnessed a massive 13.7% H1 increase in traffic to 28 million passengers and a 2.2% rise in cargo to 1.09 million tons. The 4.7 million passengers using the airport in June was 16% up on last year. The airport’s capacity will increase to over 75 million when the new Concourse 3 opens in Q1 2013. The ground facilities will be able to cope with increased demand but what about the air space?

As the international sanctions imposed on Iran begin to bite, its currency has fallen over 30% this year and its trade is grinding to a halt. Consequently, Iranian investment in Dubai reality has fallen 25% in H1 to US$ 410 million from last year’s figure of US$ 520 million. It is reported that the devaluation in the rial has left Dubai traders being owed nearly US$ 300 million by Iranian buyers.

As the eurozone crisis is now in its fourth year, the chances of an effective solution recede by the day as the so-called decision makers dither from one meeting to another. Recent data indicates that the 88.2% ratio of government debt to GDP in the seventeen beleaguered countries is now at historical highs.

The financial markets have seen the writing on the wall for some time and are now turning on Spain, the world’s number 12 economy.  As the country wallows in its third quarter of recession, with no end in sight, unemployment at 25%, youth unemployment at 50%, regional governments declaring bankruptcy and a 10 year bond rate hovering around the 7% level, it will have to join Greece , Ireland and Portugal in seeking a financial bailout.

More disturbing is the fact that depositors are losing confidence and have already withdrawn US$ 200 billion (equating to 16% of the country’s GDP) from Spanish banks in the first five months of the year.

Can it be long before countries like Spain start asking Should I Stay or Should I Go from the eurozone?

Posted in Finance | Leave a comment

Go Your Own Way

It seems that Dubai is progressing well in its quest to reduce the number of private vehicles on the roads by making its mass transit more accessible to users. Latest figures show that more than 10% of the population now use public transport (up from only 6% two years ago) with over 208 million passengers recorded in H1. Of that number, 94 million used taxis, 54 million public buses, 53 million the metro and 7 million water transport.

Another feather in Dubai’s cap came with the news that it will host the prestigious World Energy Forum 2012 in October. This will be the first time that the convention has not taken place at the UN in New York and will prove to be an eventful period for the emirate’s hotels as attendees will include ministers, ambassadors and other high flying dignitaries.

A recent report has indicated that Dubai has over hotel 11,000 rooms in construction phase which will add to its current inventory of over 75,000 rooms in its 580 listed hotels. These will be sorely needed if the annual growth (23% last year) continues in the same upward trend.

The real estate sector continues to be a harbinger of positive news for the local economy. The value of residential property transactions in H1 was over US$ 1.9 billion of which US$ 1.1 billion related to Q2 activity. An additional 6,100 new units, ready in H2, will bring Dubai’s villa inventory to nearly 65,000 whilst the number of apartments will increase by an additional 12,000 to 414,000 over the same period.

The end of July marks Q2 reporting season for local companies and so far so good. The country’s largest bank, Emirates NBD, came in with H2 profit up a massive 274% to US$ 490 million. The bank’s total assets (US$ 81 billion), customer loans (US$ 57 billion) and customer deposits (US$ 56 billion) were all heading north. In addition, Etisalat announced a 17% Q2 profit increase to US$ 520 million after several quarters of declining returns, with Revenue rising 4% to US$ 2.25 billion.

The DFM Index started the week at a bullish 1536 but as fresh eurozone problems emerge, it weakened almost  2% to close at 1510 – albeit on thin trading of around a daily US$ 35 million. Whilst the beginning of July had seen a mini revival in the local bourse, this will not help some brokerage firms from going out of business. The number of entities has halved since last year and it will be no surprise to see this current figure of 50 halving again before the end of the year.

As global economic gloom continues unabated, there has been a significant easing of investor concerns about the state of Dubai’s creditworthiness. This is reflected in the fact that the cost of insuring Dubai’s sovereign debt is at its lowest point since November 2009 with 10 year bond yields heading well south of 5%.

This rate compares favourably with eurozone countries such as Greece (27.48%), Spain (7.37%) and Italy (6.44%).

Just to confirm that the eurozone is going down the toilet, its lynchpin, Germany, was left reeling with the news that Moody’s had lowered its credit outlook from “stable” to “negative”. Maybe the markets – and apparently most of the world – know more than the vacillating decision-makers who are responsible for this economic mess. It is probably too late for the leaders to be more proactive, rather than reactive, in their approach to solving this massive debt crisis.

To add to the global economic problems, the unusual weather patterns are affecting food supply. Unprecedented drought conditions in the US are being held responsible for soaring food prices, including record highs for both corn and soybeans, and furthermore wheat prices have risen over 50% since the beginning of June. European heat waves have resulted in similar problems. The end result is that there will be inevitable food price hikes everywhere and a situation far worse than the 2008 global food crisis which was the catalyst for social unrest and political changes in so many countries.

As some wise economist pointed out – if the whole world is stuffed then we are all stuffed.

Over the coming weeks, Greek, Spanish and Italian leaders may well be told by the other eurozone countries to “Go Your Own Way”. Whether they do  or not remains to be seen but time is rapidly running out for all stakeholders involved in this debacle, which has got the potential to bring the world to unprecedented political turmoil and social unrest. 

Posted in Finance | Tagged , , , , , | Leave a comment

Stand and Deliver!

With the summer heat taking its toll, it comes as no surprise that UAE energy consumption rose 5.2% last year to a frightening level of 1.56 million equivalent barrels a day. Evidently its recent growth rate is amongst the highest in the world – in 2008 there had been a 23% annual jump.

As the mercury seems to be settling in the 40 degrees plus range, the sun is definitely shining on the local retail sector. Although final figures have yet to be announced, it seems that the 2012 Dubai Summer Surprise festival could turn out to be the best ever as some malls report up to 20% increase in business. That being the case, it could add more than US$ 5 billion to the Dubai economy.

There is no doubt that hotels have also felt the benefit from the DSSF with a high number of visitors especially from the GCC countries. H2 will see a further 4,500 units added to the current stock of 54,000 rooms followed by an additional 11,000 rooms between 2013 and 2014.

There were two significant events this week. The first was the formal approval by the Emirates Nuclear Energy Corporation to start work on Units 1 and 2 of the Barakah Nuclear Facility. Each of these Korean-designed reactors will be able to produce 1,400 megawatts of electricity.

The second was the inauguration of the 400 km long pipeline from Abu Dhabi to Fujairah. On its first operational day, 500k barrels of oil were pumped through the new link which has a capacity of 1.8 million barrels or about or 70% of the country’s daily production. One of its major benefits is that it will bypass the Strait of Hormuz and any future problems that could arise.

Despite the fact that it currently produces 2.6 million barrels a day, the UAE has the highest petrol price in the Gulf. At US$ 0.41 a litre it is more than three times dearer than Saudi Arabia’s price of US$ 0.12. Only two countries in the Arab world charge more – Syria (US$ 0.56) and Tunisia (US$ 0.70).

These relatively high petrol prices have not deterred the impressive growth in motor vehicle sales. Al Futtaim – the biggest dealership in the country – reported a 27% half yearly rise in its Toyota sales which equate to annual sales of 100,000 units. Over the same period local Ford sales are up 38% whilst GM have posted an 11% gain.

The Dubai feel good factor even spilt over onto the local bourse which saw a weekly 3% rise from 1491 to 1536. The DFM Index is showing a 13.47% YTD gain – not a bad result during these turbulent  times!

Despite the local bullish outlook, this week has seen yet again increasing concern about a slowdown in global growth which, as noted in previous blogs, is now impacting on emerging markets. Consequently the IMF has again cut its 2012 growth forecasts for China to 8.0%, India 6.1%, Russia 4.0% and Brazil 2.5%. Eurozone remains a basket case with an overall projected contraction of 0.3%. More disconcerting is that in April, Italy and Spain were forecast to have negative growth of 0.3% and 0.6% respectively – three months later, the IMF cut these even further to minus 1.9% and minus 1.5%! Despite its US$ 16.5 trillion debt problem, the US has seen its latest growth forecast shaved by only 0.1% to 2.0%. (The worst is yet to come for that country).

In contrast, the Middle East’s growth forecast remains at 3.7%.

Scarcely a day goes back without another story on the woeful state of the banking industry. The latest episode in the on-going saga involving HSBC and its relationship with Mexico and money laundering where in 2008 over US$ 7 billion was shipped from its Mexican operation to the US. It seems that US HSBC affiliates were able to forward funds to prohibited countries such as Iran, Sudan, Burma, Cuba and N Korea. The good news for all concerned is that the bank has now expressed remorse about their unacceptable behaviour which had been going for more than a decade! The bad news is that they will probably get away with a fine of up to US$ 1 billion.

This week, the largest bank in the USA reported that it had lost US$ 4.4 billion as result of the antics of its rogue trader, the “London Whale”. As intimated in a May blog, we thought the then reported loss of US$ 2 billion to be on the low side! Little wonder that since April, the market has wiped off nearly US$ 40 billion from the bank’s value. To add to their problems, JP Morgan are now embroiled in an investigation that they have been manipulating the Californian energy market for their own profit and to the detriment of the public.

Not to be outdone US credit card companies – including Visa and MasterCard – have agreed to pay more than US$ 6 billion to retailers for basically ripping them off with fixed high fees. And we worry here when small unexplained charges appear on our statements and nothing gets resolved by the bank.

The repercussions from the Libor crisis rumble on. Although Barclays were the first to be caught by the authorities and fined a derisory US$ 450 million for fraud, there are many other banks waiting in the wings to receive their punishment with possible much higher fines. And rest assured these fines will seem miniscule once the lawyers start suing for all the damage suffered by their unsuspecting clients.

Don’t forget that earlier in the year, Barclays were fined US$ 12 billion for giving bad financial advice to its UK clients. It had understated the risks involved from investing in two Aviva funds which subsequently suffered heavy losses in the 2008 GFC.

Gone have the days when bank robberies were carried out by persons stealing from banks. These days, it seems that the boot is on the other foot and banks are getting their own back by continually dreaming up ways of defrauding their customers. Stand and Deliver now has a whole new meaning!

Posted in Finance | Tagged , , , , , , , , , , | Leave a comment

We’ve Only Just Begun

The impact of the eurozone debacle, slow worldwide growth and the fact that global banks are cutting back on lending are all reasons why this area is now facing a meltdown in bank lending. Staggering figures out this week have revealed that Middle East syndicated lending for H1 2012 touched US$ 190 million – a frightening 98% fall from US$ 10.2 billion a year earlier. Five years ago, ME corporate lending had hit a massive US$ 144 billion.

There is some little respite in the fact that debt capital markets are picking up some of the shortfall with a 50% year on year increase to US$ 17 billion.

Following nearly two years of talks about the restructuring of Dubai Group’s US$ 10 billion debt, it seems that some of the banks have lost patience and are considering withdrawing from further discussions. The impasse has arisen despite other government related entities having already refinanced their debt this year. These include JAFZA (US$ 2 billion), DIFC (US$ 1.5 billion) and Dubai Holding (US$ 500 million).

Jordan Dubai Capital, a subsidiary of Dubai Capital, was established in 2005. A Hong Kong private investment fund, HPF, paid US$ 135 million for the acquisition of a company that was based in Amman.

Whilst one local group is cashing in another is splashing out. Jumeirah Group is reported to have expensed US$ 80 million for a 25-year management contract to run a new 180-room hotel in Baku, Azerbaijan. The Jumeirah Bilgah Beach Hotel is the latest addition to the Group’s portfolio which reached 20 properties with this week’s opening of the Dubai Duty Free-owned Jumeirah Creekside Hotel.

Another company may have to reach for its cheque book if it is successful in Afghanistan’s second ever oil auction, covering certain blocks in the north. Dragon Oil, 51% owned by Dubai government via ENOC, is one of eight companies that have been approved by The Afghan Ministry of Mines.

One more organisation  after your money is the Dubai developer, Range Developments. The firm is planning to build a US$ 200 million hotel on St Kitts and Nevis and are looking for investors who are willing to buy a share in the project.

Last week’s blog noted the boom in tourists which had resulted in a 10.4% year on year increase in passenger numbers at Dubai airport, bringing the YTD total to 23.2 million. Consequently it was no surprise to see that Dubai Duty Free announced an 11% increase in sales of over US$ 770 million for H1 2012.

The fact that summer is here can be seen from the latest hospitality figures with May hotel occupancy dropping to 79% (from a March high of 89%). Although there has been a 13% increase in RevPar (revenue per available room) over the first five months of the year, May did witness a monthly drop in the average room rate from US$ 290 to US$ 204.

One Dubai sector not bothered about the heat is real estate. The Al Barari development has just announced the release of 33 villas with a price range of between US$ 5.5 million and US$ 9.5 million. Obviously there are still some investors who have yet to hear of the coming of the second GFC!

This comes at a time when the local property market is at the beginning of quite a revival. Reports indicate that some locations have seen annual price increases of 20% – such rates have not been seen since the halcyon days of 2008.

The emirate’s biggest developer, Emaar Properties, is reported to be looking at issuing a US$ 2 billion sukuk to help future expansion plans. Last month the company launched its newest residential project, The Views – with 224 apartments – which sold out in a day.

Emaar’s shares are currently trading at US$ 0.84 – almost the same level as this time last year. The DFM Index closed the week down 19 at 1491 in fairly lacklustre trade as the holy month of Ramadan approaches.

Conflicting fortunes for two locally-based engineering-related companies. The Australian firm, Hastie Group – with 7,000 employees of which 20% worked here – went bust in May. It had reported a US$ 150 million loss in H2 2011 and an “accounting irregularity” of almost US$ 20 million, apparently perpetrated in Brisbane. Now it seems that their former CEO, Bill Wild, is apportioning much of the blame for their demise on a series of bad acquisitions in the Middle East. So much for due diligence!

Meanwhile UK-based Driver Group has seen their revenue rise 35% in the six months to March 2012 mainly because of a 50% surge in ME operations. (This comes on top of news that Balfour Beatty last month reported that major improvements in Dubai had helped the company maintain its order book at around the US$ 23 billion level).

On a global level, the big four emerging markets – BRIC – are seeing a worrying downturn, the speed of which  has surprised many analysts. Q2 saw nervous investors withdraw hundreds of millions of dollars from related stock funds. It seems that not only the eurozone crisis is having an impact on continued growth in these markets but also the deteriorating US economy.

The old Berlin Wall was a symbol of the political separation between east and west Europe. The new Berlin Wall is an economic symbol beginning to divide north and south Europe. One just has to compare the government credit ratings and bond yields of the different eurozone countries to see that it will be only a matter of time before there are at least two currencies in the eurozone. The 10 year bond rates highlight the widening gap – Greece at 25.51%, Portugal 10.58%, Spain 6.83% against Germany’s 1.32%, Netherlands 1.70% and France 2.25%.

The alarm bells have been ringing for some time but have fallen on deaf ears. In relation to the real trouble, it’s true to say that we’ve only just begun.

Posted in Finance | Tagged , , , , , , , , , | Leave a comment

Diamonds are Forever

The UAE has ticked all the right boxes to claim regional bragging rights, by bettering all of its neighbours, in the recent World Economic Forum’s Global Enabling Trade Report 2012. On a worldwide comparison, it was ranked in terms of quality of:

  • air transport infrastructure – 4th
  • seaport infrastructure – 6th
  • transhipment connectivity – 7th
  • transport infrastructure – 11th
  • border administration – 11th
  • business environment – 12th

Such reports just go to highlight the immense progress that has made Dubai such a vibrant regional tourist, trade and retail hub.

The retail sector will add yet another facility to its portfolio with the proposed US$ 7.5 million Jumeirah Park Community Centre, covering nearly 11,000 sq mt. Although not in the same league as the likes of Dubai Mall (the world’s largest at 350,000 sq mt), Mirdiff City Centre (290,000 sq mt) and Mall of the Emirates (225,000 sq mt), it will serve over 4,000 residences in the Jumeirah Village triangle.

Then there is the US$ 160 million expansion plan of the Dragon Mart. Already the world’s biggest trading centre for Chinese goods outside of China, it is looking at an additional 177,000 sq mt extension. Interestingly, it is reported that over 80% of the extension has already been pre-let!

Also going well (maybe too well) is local real estate. It is estimated that Dubai has over 400,000 apartments and 58,000 villas with a further 6,000 houses (or over 10%) becoming available in H2 of 2012. If reports are to be believed, there are some areas that have seen a whopping 10% QUARTERLY increase in prices – that being the case, it can only be hoped that this not a precursor of another property bubble, which all but destroyed the market in 2008.

Commercial realty is a different story with there still being a 40% vacancy rate. A further 800,000 sq mt is expected to be added to the inventory in H2 bringing the total amount of Dubai office space available to nearly 10 million sq mt.

As the temperatures hover in the mid-40s and the utility bills rise in unison, DEWA continue with their expansion plans. This time it will spend US$ 55 million laying over 800 km of cable to add to the electricity grid.

It seems that Meydan is also turning up the heat with their reported claim for US$ 950 million against Arabtec and the Malaysian contractor WCT in relation to the construction of the mega racecourse which hosts the Dubai World Cup. This follows an apparent acrimonious dispute that saw the cancellation of the original contract in 2008.

That year also saw the QE2 berth in Dubai and four years later plans are finally afoot to recoup some of the US$ 100 million investment. Now – with its original fittings and décor intact – it is to become a luxury floating hotel with 300 hotels and another must see landmark for the increasing number of Dubai-bound visitors.

The boom in tourists is mirrored in the May 10.4% year on year increase in passenger numbers at Dubai airport. The monthly figure of 4.4 million brings the YTD total to 23.2 million and in line with the annual forecast of 56.5 million passengers in 2012.

Another Dubai success story is Byrne Equipment Rental which accounts for over 20% of all equipment hired in the UAE. The company, valued at US$ 320 million, is set to build a new US$ 4 million HQ in Dubai Industrial City.

It is no secret that car dealerships have had a bumper year to date and this reflects growing consumer confidence that the good old days are on the way back. Al Nabooda Automobiles seem to think so as the distributor of Porsche, Audi and VW has just announced plans to spend nearly US$ 300 million on new facilities over the next two years.

One industry that is beginning to feel the pinch from the economic turmoil is private equity. Although estimated at US$ 23 billion (having grown from a base of US$ 8 billion five years ago), the Middle East segment expanded by only 3% – or US$ 700 million – in 2011. Life is not going to get any easier as fund raising becomes more difficult to source and the local bourses continue to perform badly.

However, Majid Al Futtaim Holdings LLC is a company with no apparent problems raising finance. This week it managed to sell US$ 500 million bonds at 5.25% and actually received bids in excess of US$ 3 billion. Likewise Dubai Duty Free managed to raise US$ 1.75 billion by a 6 year senior unsecured syndicated credit facility which was heavily oversubscribed. Both these deals indicate that Dubai debt has recovered from the dark days of November 2009 and has regained market confidence.

The DFM had a better than expected week of trading with the Index closing on Thursday at 1505 – heading north from Sunday’s opening of 1452. The Index is showing an 11.1% YTD improvement from its opening then of 1353.

Meanwhile, the Central Bank reported a 1.5% reduction in May money supply aggregate M1 (total of current and call accounts deposited with the banks) to US$ 77 billion. With quasi-monetary deposits of US$ 150 billion added to M1, money supply aggregate M2 fell just over 3% to US$ 227 billion. When government deposits at local banks of US$ 60 billion are added to M2, the money supply aggregate M3 sees a 1.3% decrease to US$ 287 billion.

Although bank deposits slipped 1.2% to US$ 306 billion, there was a marginal increase in May total bank loans and advances to US$ 292 billion. This indicates a tightening in liquidity which, if continued, could prove to have a negative impact on future growth; at the moment, the non-oil sector is slowing down and the banks’ Q2 reporting season profits will inevitably be disappointing overall.  But on a global comparison, Dubai is still tracking reasonably well.

On the world stage, the eurozone debt crisis still dominates the news with little or no hope for a permanent solution to all of its problems whilst the politicians are involved in micro rather than macro-managing the situation. The crisis deepens by the day and can only be rectified by a combination of fiscal and political integration with fundamental changes to the whole system, including the establishment of a federal central bank.

Eurozone now has a 1 in 9 unemployment rate (17.6 million) – the highest since the euro was launched back in 1999 – and youth unemployment has reached 22.6% (3.4 million). The Greek youth unemployment rate is over 50% whilst Italy stands at 36.2%. When you add the figures from the other ten EU countries not in the 17-member eurozone, there are 24.9 million (10.3% of the work force) unemployed including 5.5 million youths (22.7%).

And which country is the current president of this mess – Cyprus!

Two examples from the corporate world company highlight that it is not only the eurozone crisis that is causing economic mayhem. Microsoft bought aQuantive in 2007 for US$ 6.3 billion and now it has just written off this balance indicating the worthlessness of the acquisition. The British pharmaceutical company, GlaxoSmithKline, has settled a US$ 3 billion case for being involved in healthcare fraud in the USA. And then there is Barclays.

As intimated in a recent blog, Bob (I Love Barclays) Diamond, the erstwhile CEO of Barclays, finally did fall on his own sword. His Tuesday resignation, following revelations of a Libor rigging scandal by the bank, surprised some analysts and came as the bank faced possible criminal action. It is hard to imagine that other major players are not involved as Barclays was the first to raise their head above the parapet, admit their wrong-doing and settle with the authorities. Who said Diamonds are Forever – not so for the one who gets paid so much for appearing to know so little!

Posted in Finance | Tagged , , , , , , , , , , | Leave a comment

You Can’t Always Get What You Want

Just as the rest of the world appears to be wallowing in an economic malaise, Dubai Customs report that Q1 trade reached an impressive US$ 81 billion almost 7% up on the corresponding period last year. Exports and Re-exports rose 9% to over US$ 33 billion whilst Imports reached US$ 48 billion – 1% higher than in Q1 2011.

India is still the top trading country with total trade at almost US$ 11 billion – almost half of which were exports. This made India Dubai’s second biggest exporter but well behind China which exported US$ 7 billion worth of goods. Unsurprisingly gold was not only the biggest imported item with the yellow metal accounting for over 14% of total imports (or US$ 7 billion) but also the emirate’s biggest export at US$ 5 billion.

Undoubtedly such figures spark investor interest in Dubai and are a factor in the 22% year on year increase in the number of business registration and licensing transactions (54,286) carried out by the Department of Economic Development. May also witnessed a 14% increase in the number of trade licences issued. Such figures only go to prove the increasing resilience of the local economy.

One reason expounded for Dubai’s success is its development of modern customs systems which has resulted in the emirate becoming more competitive on the global stage. Indeed the World Economic Forum placed the UAE third in the world in its Global Competitiveness Report 2011 – 2012.

The tourism sector received a boost with the planned 2013 opening of a Marvel Comics indoor theme park. Built by the IMG Group (Ilyas and Mustafa Galadari), it will be located at their City of Arabia development and will cover 1.2 million sq ft.

Even without the attraction of such a theme park, tourists are flocking into the emirate not only for a pre-Ramadan break but also to enjoy the shopping and ancillary activities of Dubai Summer Surprise. Last year, DSS attracted 4 million visitors who spent an estimated US$ 2.4 billion and it is hoped that this number will be surpassed in 2012.

It is not only tourism but also real estate sector that is beginning to regain some of its former glory with even more land being made available to overseas investors. Sheikh Mohammed bin Rashid Al Maktoum released two plots of land in Dubai Investments Park on an 85 year leasehold. This will surely bring in overseas buyers looking for a secure and profitable investment and should be a win win situation for both sides.

Arabtec finally signed a US$ 3 billion contract to construct the Midfield Terminal Building at Abu Dhabi International Airport. The 700,000 sq mt terminal building will be able to accommodate 65 aircraft and 8,500 passengers an hour.

Further good news came from two other major companies – Anham and Nestle. The former, a Dubai-based company, has just been awarded an US$ 8 billion contract for supplying American troops in Afghanistan. This comes on top of the same company being awarded a US$ 2.2 billion 2010 contract for logistical support to US troops in Iraq, Kuwait and Jordan.

Nestle announced that it was building a new US$ 135 million factory that will create an additional 800 jobs. The new facility will be on a 175,000 sq mt block at Dubai World Central and will make coffee and culinary products.

Not a bad week also for the Iraqi entrepreneur, Ihsan Jawad, who sold his intelligence and information group, Zawya, to Thomson Reuters for a reported US$ 40 million. The company was launched in Dubai ten years ago.

Also in the selling mode was Shehab Gargash, the owner of Daman, the Dubai investment management group. The company offloaded 22.7% of its shares in a private deal estimated at US$ 27 million. If the market continues to improve, the company will look at an IPO with a possible listing on one of the UAE markets. (One bourse that could do with the business is Nasdaq Dubai, which since the May delisting of Damas, has only two stocks trading).

One of those two listed companies, Depa Limited, has just lost a US$250 million fit out contract for the Doha International Airport. This blow to the interior design company comes on the back of losing US$ 50 million as their related performance bond and advance payment guarantee were encashed.

Meanwhile, the DFM had another flat week of trading with the Index closing on Thursday at 1452 – heading down from Sunday’s opening of 1470. As already indicated in earlier blogs, the market will remain stagnant until there is some action from European leaders on solving their sovereign debt crisis.

Dubai and the region are in the middle of a boom in debt market trading with bond sales this year already in excess of US$ 18 billion. The easier availability of credit and the growing confidence in Dubai’s creditworthiness have made the emirate a safer haven than most other locations in the world.

With the announcement that Emirates will help finance the imminent arrival of four Airbus 380s as part of its current order of fifty-eight, the airline will arrange a US$ 1 billion financing facility. Nearly US$ 600 million will be part of a leasing agreement across two tranches – with 75% having a 10 year maturity and the remainder with a 6 year maturity. Last week, the airline had repaid a US$ 550 million sukuk on maturity.

The UAE Central Bank indicated a 30% rise in banks’ non-performing loans (NPLs) for the twelve months ending 30 April 2012. There was a paltry 1.7% increase in loans to nearly US$ 300 billion whilst NPLs soared 30% to over US$ 16 billion. (What is left in the woodwork remains to be seen).  Total bank assets saw an almost 3% jump to over US$ 460 billion.

Overseas, certain banks have been taking a pounding this week. Barclays was fined US$ 450 million for trying to manipulate the Libor rate (some may call it cheating). Just wait for the lawyers to get their teeth into lawsuits and then Barclays problems will escalate exponentially. What is even more disquieting is that it is expected that other banks may be in the same trouble.

JP Morgan, having thought they had  lost US$ 2 billion in May from their credit derivatives debacle, may have to revise this estimate to a much higher figure. So much for betting in credit markets!

The two banks’ respective CEOS, Bob Diamond and Jamie Dimon, must be in danger of losing their jobs.

Whilst the outlook in Dubai is bullish, the same could not be said for many other places – none moreso than the euro zone which appears to be spiralling into deeper economic turmoil. If the political leaders cannot agree on basic fundamentals to try and lessen the crisis then the odds must be in favour of certain countries leaving the euro this year.

Unlike Portugal, Ireland and Greece, which have been hit hard by austerity packages as part of their bailout agreements, Spain seems to have been able to negotiate a much more equitable deal. This just shows that you can’t always get what you want but if you try sometimes you get what you need – but for some high profile banks that should read “you get what you deserve”.

Posted in Finance | Leave a comment

You Keep Me Hangin’ On

Further signs of the region bucking the global trend came with the news that Gulf cement companies saw a 24% Q1 increase in Revenue to US$ 1.25 billion whilst their profits rose by 21% to US$ 435 million. UAE-based companies had a welcome 8% rise in Revenue to US$ 260 million over the same period.

An interesting fact from the Dubai Statistics Centre revealed that on a daily basis more than 1 million people (day visitors, tourists, workers from other emirates etc) come to Dubai – boosting the actual population by 50% to over 3 million. This indicates the growing importance of the city’s standing as the regional business and tourism hub and augurs well for future growth.

The nation’s CPI saw a monthly 0.21% rise and a 0.81% increase over the May 2011 figure. Dubai’s monthly increase was 0.35%.

The 12-nation OPEC, which pumps about 40% of the global oil, recently reported record export earnings for its members, with UAE as its second largest earner (after Saudi Arabia). The syndicate’s income in 2011 was in excess of US$ 1 trillion and 33% up on the preceding year with the UAE accounting for over 10% of that figure, well behind Saudi’s income of US$ 310 billion.

A good indicator of the turnaround in the local economy was that Eros Group, one of the leading distributors of electronic goods, forecasts a 30% + growth in Revenue this year to over US$ 800 million. Consequently, they are looking at expanding on their existing 30 stores and recruiting more staff in the UAE.

The population growth has also seen a boost in the healthcare sector which some estimate that increased spending in the UAE will top US$ 17 billion by 2015. It currently contributes about 3% to GDP. Little wonder then that Dubai-based Landmark Group is planning a US$ 30 million investment with plans to open 20 clinics around the country.

Property developer, Damac, resuscitated its old pre-GFC marketing ploy to try and drum up business. Then it would regularly throw in gifts – such as Porsche cars, apartments and even a tropical island – to entice potential buyers. Now it is back giving away jet-skis, Monterey cruisers or yachts (worth in excess of US$ 1 million) to all buyers, depending on the value of the property.

On the subject of property, the Real Estate Regulatory Authority (RERA) has announced that all Dubai-based companies will now be required to register their property lease agreement which will be completed on their Ejari online system. Of the 115,000 contracts already registered, 64% are residential whilst the remaining 36% are commercial.

You can never keep Emirates Air Line out of the news. Now it is the imminent opening of London’s newest attraction – their cable car system which will straddle the Thames between Greenwich and the Royal Docks. Emirates have invested nearly US$ 60 million in a ten-year sponsorship agreement and this can only enhance their growing presence in the UK.  Because of their flying 100 times a week into the country, some estimates indicate that it contributes over US$ 400 million to the British tourist industry.

This week, Emirates fully repaid a 7-year US$ 500 million sukuk and this shows that the airline is on a sound financial footing. As with other global carriers, the airline is feeling the pinch as a result of high oil prices and the volatile market that have seen prices hover between US$ 91 and US$ 128 over the past quarter. Obviously high oil prices have a negative impact on the industry with higher ticket prices and fewer customers (both passengers and cargo). Today’s Brent crude oil price of US$ 91 is the lowest in eighteen months and a reflection on the sorry state of the global economy. Whether this leads to cheaper air fares is problematic.

As expected, MSCI, the international index provider, once again decided not to upgrade Dubai Financial Market from frontier to emerging market status which would have introduced billions of dollars of new investment on the local bourse. Although satisfied that most of their requirements – including market accessibility, clearing and settlement issues – had been met there was still some concern about the trade settlement system.

Meanwhile, the DFM had another uneventful week of trading with the Index closing on Thursday at 1470 – slightly up on the Sunday opening of 1464. Having risen by some 24% in Q1, the Index has fallen back somewhat since then and is now registering an 8%+ YTD increase. The market will remain stagnant until there is some action from European leaders on solving their sovereign debt crisis.

Wherever you look there is nothing but negativity. Corporate and consumer confidence in India continues to fall as the rupee drops to a historic low of 56.55 to US$ 1. China sees its factory sector slump for the eighth straight month whilst its export orders are at the lowest in three years. The US Federal Reserve acknowledge a much weaker than expected economic outlook with increased unemployment and little growth. And then there is Europe!

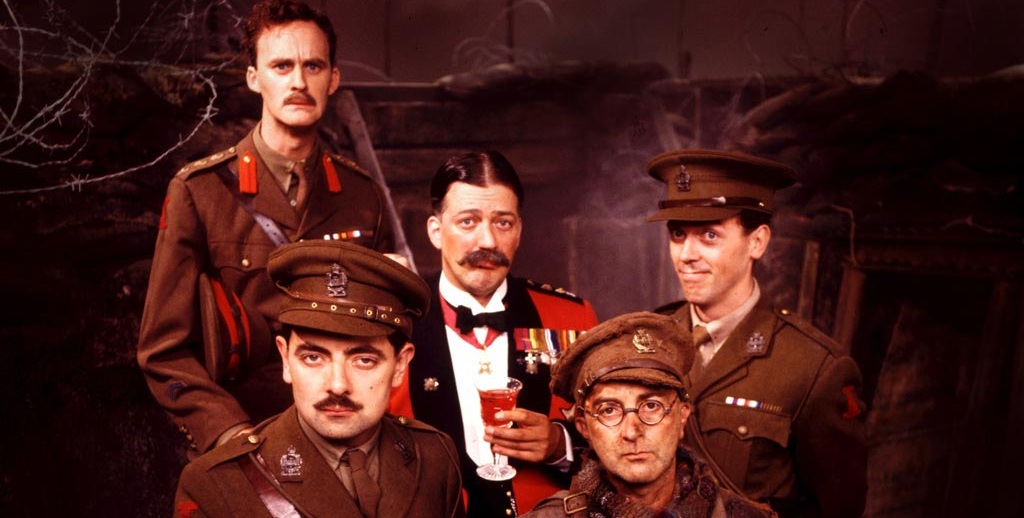
Much has been written on the Euro crisis but not as succinct as the following excerpt.

The Euro according to Black Adder

Baldrick: “What I want to know Sir is, before there was a Euro there were lots of different types of money that different people used. And now there’s only one type of money that the foreign people use. And what I want to know is, how did we get from one state of affairs to the other state of affairs”

Blackadder: “Baldrick. Do you mean, how did the Euro start?”

Baldrick: “Yes Sir”

Blackadder: “Well, you see Baldrick, back in the 1980s there were many different countries all running their own finances and using different types of money. On one side you had the major economies of France, Belgium, Holland and Germany, and on the other, the weaker nations of Spain, Greece, Ireland, Italy and Portugal. They got together and decided that it would be much easier for everyone if they could all use the same money, have one Central Bank, and belong to one large club where everyone would be happy. This meant that there could never be a situation whereby financial meltdown would lead to social unrest, wars and crises”.

Baldrick: “But this is sort of a crisis, isn’t it Sir?”

Blackadder: “That’s right Baldrick. You see, there was only one slight flaw with the plan”.

Baldrick: “What was that then, Sir?”

Blackadder: “It was bollocks”.

Whilst the European leaders keep everybody hangin’ on, there is no doubt that the global economy can only move in one direction – and it is not up!

Posted in Finance | Tagged , , , , , , , , , , , , | Leave a comment

Paint It Black

ImageIt comes as no surprise to hear of the IMF warning that the UAE could be hit by further deterioration in the eurozone crisis. Their report specifically highlighted Greece as the major source of “contagion risk” for Dubai and added that Italy, Portugal and Spain could also add to the emirate’s woes.

The Spanish Prime Minister, Mariano Rajoy, has finally realised that his country needed to be bailed out to try and save its exposed banking system which has been saddled with at least US$ 240 billion in dicey real estate loans. Whether the requested US$ 125 billion is enough remains to be seen and I guess a stronger firewall – maybe ten times this amount – will be needed to stop the crisis spreading to other countries. But what should be clear to the authorities is that if this bail-out fails, it will lead to a global economic catastrophe. However, as the less than proactive eurocrats have done very little since the euro crisis started in Greece over two years ago, the outlook is indeed bleak.

It does seem ironic that as Dubai recovers from the GFC and has metaphorically taken its medicine over the past three years, it now may be forced to take another dose because of the failure of other countries to look after their own economic health.

As business confidence plummets around the world, the annual IATA meeting in Beijing spreads even more doom and gloom. The industry has been hit by a triple whammy of high fuel prices, Europe’s sovereign debt crisis and the political situation in the Middle East. This has seen its profits fall from US$ 16 billion in 2010 to US$ 8 billion last year with their current year forecast of US$ 3 billion – a wafer thin 0.5% net profit margin.

Whilst the air industry was meeting in its capital, the Chinese government surprised the markets by cutting interest rates by 25 basis points – its first cut since 2008! Although perhaps a sign of easing of monetary policy, it did little for the equity markets amid fears that it would fail to boost lending as their mainland banks continue to struggle to fill loan quotas.

As reports indicate that the Dubai bourse has lost in excess of US$ 60 billion since the September 2008 failure of Lehman Brothers, the Dubai Financial Market Index again remained flat starting and ending the week at exactly the same level – 1464.

Dubai-based expats will be relieved to discover that the emirate has slipped to become the 94th most expensive city in the world – down 13 places from last year. At the same time, Dubai continues to live up to its reputation as a global tourist destination, now ranked 8th in the world. It seems that it is by far the most popular of the total top ten destination cities in the Middle East and Africa; its 8.8 million visitors account for 30% of the top ten’s total of 29 million.

As part of its strategy to increase the number of visitors to Dubai, authorities are now pitching for the city to host the 2020 World Expo. It will be bidding against four other locations – Ayutthaya, Ekatrinburg, Izmir and Sao Paulo.

One of Dubai’s traditional industries – fishing – received a boost this week with the announcement of the second phase of the emirate’s Al Hamriya port development. This will include a new 1,650 metre long wharf with a capacity to accommodate 200 fishing vessels.

As Dubai’s property market sees welcome strengthening in specific areas, there was news of a further 2,000 apartments being released this month. Comprising eleven buildings, the Ritaj development is situated in Dubai Investments Park and may prove a magnet for those residents currently working in neighbouring Abu Dhabi. Although the economy is showing major signs of improvement, with investor confidence heading north, it is sobering to remember that current property prices are still 64% lower than at their peak of September 2008.

Despite the fact that there are positive factors indicating an upsurge in the local economy, it is the external factors that will cause future problems. In the short-term, this week-end’s Greek elections or any further worsening of the situation in Spain maybe the catalysts for a major spill over from the current fringe players into the heart of Europe and then into the rest of the world.

Most of Europe is in a perilous state and if Greece has to return to the drachma, Europe will inevitably go into a deep recession with the knock on effect for Dubai – further tightening of liquidity, increased lending rates and a massive body blow to the three “Ts” that have led Dubai’s economic revival, tourism, travel and trade. And what will happen to say the American and Chinese economies – both of which will be major casualties of a European economic meltdown? No wonder there are those who look at the immediate future and paint it black.

Posted in Categorized | Leave a comment

Tomorrow Never Knows

Some welcomed the fact that Brent Crude, having hit a low of US$ 93 earlier, ended the week hovering around the US$ 100 mark. As the Iranian crisis had pushed up prices earlier in the year, the European economic woes and growth contraction in China have led to the current fall – well down on the US$ 126 mark witnessed in March.

But the news is not so good for Gulf producers as some estimate that for every US$ 1 drop in price costs them an annual US$ 6 billion in lost revenue. Last year the average oil price came in at around US$ 110 and earned the UAE US$ 112 billion and contributed 39% to the country’s economy. A fall to say an average of US$ 95 per barrel will leave the country at least US$ 14 billion short on the year.

But lower oil prices, allied with the global economic malaise, will inevitably result in the country posting a lower growth this year. 3% in 2012 will be highly regarded even though it will be well down on the 4.2% recorded in 2011.

There is good news in certain non-oil sectors. Following unprecedented falls in 2010, there have been significant improvements in retail trade (up 10%), manufacturing (6%) and transport (4%). However construction is still under the cosh but managed to register a 3% expansion in 2011.

One company that will not be participating in any further growth in 2012 will be the Australian builder, Hastie Group. Specialising in mechanical and electrical contracting, the company, which had been involved in several major projects here,  has gone into administration and part of its problems seems to have been the discovery of on-going accounting irregularities of US$ 20 million. As so often is the case, this has been put down to the actions of a “rogue employee”!

One former Australian company, Multiplex, (now Canadian-owned Brookfield Multiplex) is faring better having just built the JW Marriott Marquis Dubai located on SZR. What will be the world’s tallest all hotel building at 355 metres will see the first of its two phases opening later in the year. The hotel will have over 1,600 rooms and is owned by Emirates.

Further good news for Australia came with reports that their economy grew by 1.3% in the last quarter – far better than expected. But this may present a distorted view as the incredible mining boom may be disguising problem areas in other sectors including housing, retail, tourism and exports. The high dollar rate and the fact that the top 200 companies have seen over US$ 100 billion wiped off their value since the beginning of May do little for business confidence and consumer sentiment. Like Dubai, the Aussie economy faces the same pressures that continue to arise from the eurozone crisis and a slowdown in China’s growth.

On the local front, Nakheel have reported a US$ 100 million Q1 profit compared to a US$ 10 million loss in 2011 whilst their revenues have almost tripled to US$ 370 million over the same period. This comes at the same time as an industry report indicates a strengthening of the residential sector in certain areas of Dubai.

The Dubai Financial Market Index continued with its recent lacklustre trend closing the week down 8 points to 1464 and 6% down over the last month. It is difficult to see any dramatic change for the remainder of June.

Facebook shares continue to plummet as they try to achieve a more realistic price level. An almost 30% decrease since its 18 May debut seems to indicate that the stock was well over-valued at a massive 107 times reported earnings.

On-going dismal economic data from the Eurozone continues to dog the markets. The 10 year bond rates indicate the dire mess the eurozone is in with Greece paying 28.6%, Portugal 11.5%, Ireland 8.2% and Spain 6.1% for servicing their long-term debt whilst Germany’s rate is at 1.4%. The fact that Greece is paying 20 times more than Germany says so much for a common currency!

Whilst many consider the inevitability of Greece returning to the drachma, the focus now is to try and protect Spain from the going the same way. But any bail-out attempts are fraught with danger and failure will only hasten the debt crisis further in countries such as Hungary and Italy.

Tomorrow never knows but we are entitled to ask what have the European politicians been doing about their economic crisis and, even more damming, what have the world diplomats been doing about Syria. Precious little!

Posted in Finance | Tagged , , , , , , , , , , | Leave a comment