Life Is A Highway

Jumeirah Beach witnessed two “smart” events this week. The first saw the Crown Prince, Sheikh Hamdan bin Mohammed bin Rashid Al Maktoum, attend the maiden concept flight of the world’s first self-flying taxi service. The two-seater AAT (autonomous air taxi), supplied by German company Volocopter, transports people – without a pilot – and can remain airborne for 30 minutes and reach speeds of 100 kph. The RTA is planning to use the services in the future and has enlisted US-based JDA Aviation Company to oversee preparations for AAT flights and manage safety.

Meanwhile the Costa ‘coffee-copter’ (a specially engineered drone) carried out a one day trial delivering from its Jumeirah Beach Road drive thru store to “beach” customers, within 15 minutes of ordering.

The DMCC unveiled plans of its rebranded Uptown Dubai (formerly known as Burj 2020), located at the south end of JLT. The project will comprise seven towers, with 10 million sq ft of built up space. With two ‘super-tall’ towers (each over 300 mt high) on either side of the plaza, the district will contain 3k residences, office space, a number of luxury hotels, a twin-level central entertainment plaza – bigger than New York’s Time Square – and 200 retail outlets. Phase 1 will be ready by 2020, with the final two phases slated for completion by 2024.

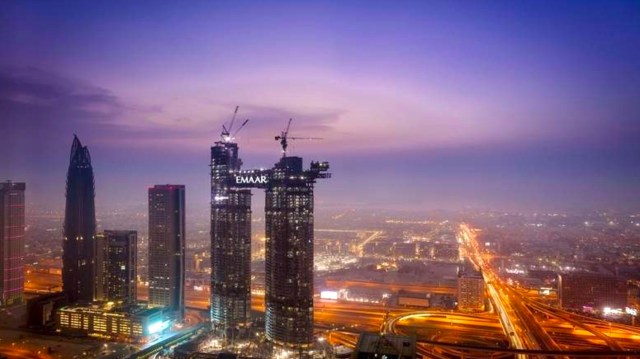
Work has started on another of Dubai’s iconic landmarks – the One Za’abeel – featuring two towers linked by what is to be the “world’s largest cantilever”. With Alec Engineering the main contractor, the twin towers (67 and 57 storeys), will have a 210 mt sky concourse – The Linx, at a height of 100 mt. Both towers will sit on seven basement levels and three levels of podium. The developer, Investment Corporation Development, expects completion by 2020.

Prescott Real Estate Development announced a US$ 45 million residential and commercial project, Prime Views. Located in Meydan Avenue, the 225k sq ft development will include 133 one-bedroom units and 18 two-bedroom units, with completion by Q4 2019. The area will also have a health club, retail and food outlets.

Arabtec’s subsidiary, Target Engineering, has won a US$ 53 million Emaar contract for phase 1 of the Forte Project in Downtown. The work involves the construction of five basements for two residential towers and should be completed by the end of Q3 next year. In July, the same company won four contracts totalling US$ 79 million.

Sales in Mohammed bin Rashid Al Maktoum City District 1 have gone well, with 520 villas already sold for a combined total of US$ 2.45 billion in its first two stages. The 267 villas in phase 1 are almost ready with the balance in the next phase completed by next year.

It is expected that Marriott will open six new regional properties in the coming months, with three destined for the Dubai market – Bulgari on  Jumeirah Bay Island, Renaissance in Downtown and a ‘W’ on Palm Jumeirah. To those who think the sector is saturated, the world’s largest hotel chain has 18 more properties in its Dubai pipeline.

Revenues and room rates continued their downward spiral into August, with latest STR figures showing declines in occupancy (down 5.9%) to 68.4%), average daily rates off 8.3% at US$ 115 and revenue per available room 134.7% lower at US$ 79. Despite YTD demand increasing by 4.8%, this was less than the 5.1% growth in new supply.

According to the latest MasterCard Global Destinations Cities Index, Dubai was ranked the fourth most popular in the world behind Bangkok, London and Paris. Last year, the emirate attracted 14.9 million visitors who spent a total of US$ 28.5 billion.

The Global Competitiveness Report ranks the UAE 17th in a listing of 137 countries in terms of competiveness – down one place from 2016. Despite this, the country is still the leading nation in the Arab world. The top three positions went to Switzerland (again), USA and Singapore.

A German study, carried out by auto parts retailer kfzteile24, has put Dubai as the second best city for driving out of more than 100 global locations! Just behind Dusseldorf, it came ahead of Zurich, Tokyo and Basel.

A Knight Frank report indicates that Dubai has the 18th most expensive global rent – at US$ 44 per sq ft – when it comes to high-rise buildings. Dubai’s rent, which has remained flat in H1 – is still some way off that of the top three – Hong Kong, New York and Tokyo at US$ 304, US$ 162 and US$ 140 respectively.

In yet another survey this week sees the country tenth in the HSBC Expat Explorer study of most preferred destinations for expats. UAE has moved up two places in the survey of 27.5k people around the world with Singapore, Norway and New Zealand in the top three places.

A report by Payfort expects the regional e-commerce market to double to US$ 69 billion by 2020, with the two main players, UAE (US$ 27 billion) and Saudi Arabia (US$ 22 billion) dominating the sector.  Some studies indicate that the UAE has the world’s highest social media penetration. (Coincidentally, the US$ 1 billion e-commerce site, noon.com, driven by the Emaar Chairman Mohammed Alabbar, goes live this Sunday).

There was no surprise to see that Dubai International recorded its busiest month ever in August with a 6.6% jump in passenger numbers to 8.23 million, compared to the same month in 2016. Despite a 1.7% decline in flight movements to 34.4k, the uptick was driven by a 7.2% hike in the number of passengers per flight to 246. In August, cargo handled reached 222k tonnes – a 10.1% month on month rise.

JAFZA posted a 2.2% increase in H1 profit to US$ 164 million despite a marginal 0.2% fall in revenue to US$ 266 million. During the period, capital expenditure was at US$ 198 million.

A Dubai Chamber of Commerce report estimated that the sale of bottled water in the country will top US$ 736 million by 2021, growing at a 9.3% compound annual growth rate. Of the current total, carbonated water accounts for just 1%, flavored water – 5% – and the balance distilled water.

Sunday will see the start of the new Excise Duty that will result in the current selling prices of both energy drinks and cigarettes doubling overnight whilst carbonated drinks will register a 50% retail price increase.

Meanwhile, October petrol prices will also change on the same day. Special 95 will see a 5.8% increase to US$ 0.555 per litre, with diesel prices up 5.0% to US$ 0.572.

DHL has announced a 4.9% hike in its regional annual general average price increase commencing 01 January 2018. The global express service provider indicated an additional rate increase for heavier (more than 300kg) and bulkier time definite international shipments.

Emaar’s chairman, Mohamed Alabbar, has been appointed a board member of Aramex; in July, several of his investment companies acquired a 16.45% in the logistics company.

By June, the federal government had a 6.7% budget surplus; YTD revenue came in at US$ 10.2 billion (equivalent to 78.4% of the 2017 total), as expenditure was lower at US$ 8.4 billion.

The country’s Q2 inflation – at 2.0% – was well down on the previous quarter’s level of 2.7%. There were increases in housing/utilities of 0.9% and food/beverages – 1.1% – whilst transport costs dipped 1.1%.

The country has launched a US$ 136 million Mars Science City project which aims to replicate a viable and realistic model of life on the Red Planet. The project, on 1.9 million sq ft of land, will include laboratories and agricultural testing facilities to be manned by a UAE team of scientists and engineers.

The UAE is using Japanese assistance in its plan to increase the region’s rainfall by cloud seeding. The researchers will follow the aircraft dispersing the seeds and measure their efficacy and a cloud’s micro-properties. The Japanese scientists, along with their local counterparts, will then further study the seeding effects in laboratory tests and information gleaned from aerial and ground-based measurements.

With its first of four planned nuclear reactors 96% complete, the UAE Energy Minister, HE Suhail Mohammed Al Mazrouei, announced it will open next year. Korea Electric Power Group is building the US$ 20 billion Barakah plant and when all four reactors are in operation, they will produce 5.6k MW of electricity every year. In its move away from fossil fuels, the country is aiming for 27% of ‘clean’ energy by 2021, rising to 50% by 2050.

The Islamic Development Bank has issued a US$ 1.25 billion sukuk on Nasdaq Dubai – its eighth on the exchange, bringing its total value to US$ 10.25 billion. The latest listing brings the bourse’s total value of sukuks to US$ 52.5 billion.

The DFM opened Sunday (24 September), at 3633 and fell 67 points (1.9%) to close the week on Thursday, 28 September at 3564. Volumes continued on the thin side, with trading of 137 million shares, valued at US$ 51 million, (cf 86 million shares for US$ 44 million, on Thursday, 21 September). Emaar Properties was down US$ 0.09 at US$ 2.31, with Arabtec down a further US$ 0.02 to US$ 0.78. For September, the bourse dipped 72 points, having started the month on 3638, whilst Emaar was only US$ 0.01 lower but Arabtec dropped US$ 0.11.

By Thursday, Brent Crude was US$ 0.73 (1.3%) higher on the week, closing at US$ 56.43, with gold continuing its recent downward trend, dropping a further US$ 6 to US$ 1,289 by 28 September 2017.

Scalia, owned by VW, has been fined US$ 1 billion by EU regulators for its role – with four other companies – in a 14 year cartel to fix truck prices. DAF, Daimler, Iveco and Volvo had already been fined a combined US$ 3.3 billion.

Fairfax Media is planning to divest itself of its Domain real estate business in a US$ 1.6 billion deal that will see shareholders receive one share in the new entity for every ten Fairfax shares owned. Australian analysts value each of Fairfax Media’s 2.3 billion shares at US$ 0.87, with one Domain share worth US$ 0.70.

Citing “continued investment in prices and infrastructure”, Aldi has reported a 17.0% slide in 2016 UK profit despite a 13.5% hike in revenue to US$ 11.9 billion. The German chain, with 726 stores in the country and plans for a further 70 this year, has a 6.9% market share and is regarded as having the lowest prices in the sector.

According to Moody’s, as it cut the UK’s rating one notch to Aa2, the country’s budget deficit will hover around 3% of GDP in the coming years and will not reach the government’s 2020 target of 1.0%. Even though the deficit has fallen dramatically since 2010, when it stood at 10%, the agency has indicated that the outlook had weakened somewhat after the fall of the Cameron regime which had pushed austerity measures a little too far. At this level, the UK will be one of the few developed countries whose public debt ratio is likely to rise – but probably no higher than 92% of GDP within the next two years.

There has been yet another Chinese acquisition of a UK tech company – this time in a US$ 750 million deal, Canyon Bridge has bought Imagination. The chip designer decided to go ahead with a sale after its largest customer, Apple, announced in June that it would stop buying its products.

To some, Ryanair have been flying close to the wind for some time and their day of reckoning has arrived. The CAA, Civil Aviation Authority, had threatened the Irish budget airline with legal action for “persistently misleading” passengers about their rights, following the early September announcement of 50 daily flights to be cancelled until the end of October and this week’s suspension of 34 routes during the winter season. In all, the total number of affected customers amounts to 800k.

This week the US authorities slapped a draconian 220% import tariff on the sale of Bombardier C-Series jets that could impact on thousands of jobs in Northern Ireland. Consequently, the UK government has reacted warning Boeing, the instigator of the complaint, that its status as a ‘long-term partner’ is at risk. The US company is also having legal battles with Airbus, as both sides accuse each other of taking advantage of government subsidies. No wonder then that The Economist called Boeing’s action “a flight of hypocrisy”.

One UK industry that will benefit from Brexit is sugar beet. For the first time in fifty years, it will be in a position to produce and sell as much sugar as it wants; on the other hand, European competitors from the likes of Germany and France can do the same. Incidents, like what happened in 2015, will not happen again; because of a bumper harvest, British Sugar produced 1.4 million tonnes but could only sell 1.06 million tonnes, having to store the balance (at great expense) for the following year. 60% of the UK’s 2 million tonne consumption emanates from UK sugar producers, with 15% from the EU and the balance from the rest of the world.

If anyone was questioning the efficacy of Chinese companies, they will just have to note that the country’s August industrial profits jumped 24.0%, year on year, to US$ 101 billion – its highest increase in four years and 16.5% higher than July’s return. The main driver is a government-backed construction boom that has seen building material prices ratchet higher.

Fitch Ratings has concerns about China’s high debt levels and warned of the distinct possibility of local government bond defaults and its contagion effect on the global economy. The bonds, issued by Chinese local government financing vehicles (LGFVs), have increasingly utilised the country’s shadow banking sector, especially after official lines of credit diminished, as the central government introduced stringent regulations. It is estimated that LGFV debt equates to 5.4% of China’s GDP and that a massive US$ 605 billion of such bonds have been issued since 2015.

The Asian Development Bank has amended its April 6.5% growth forecast for China to 6.7% (and its 2018 from 6.2% to 6.4%); this is in line with the IMF’s latest estimates. In H1, China’s growth was at 6.9%, driven by impressive service growth, improving exports and strong domestic consumption. However, there are concerns that rising debt levels and the move to a more market and services-driven economy may drag growth rates lower; it is noted that S&P’s worries saw the agency cut China’s sovereign credit rating to A+ from AA-.

In August, with apparent self-interest in mind, the Brazilian government agreed to open up a vast 46k sq km Amazonian reserve (as big as Denmark) to commercial mining. Following indigenous and global concerns about the environmental damage that would result, the President Michel Temer decree has been revised to prohibit mining in conservation or indigenous areas.

The Bank of England has forecast that if there were a sharp economic downturn, the banks could lose US$ 41 billion on their lending on credit card and personal loans. This could happen if interest were to suddenly rise and there was a spike in unemployment levels. As there are worries in the increase in consumer debt, it has requested UK banks to hold an extra US$ 13.7 billion to guard against the increased “pocket of risk”. As inflation levels are nearer 3% than the BoE’s 2% level, expect interest rates to probably double to 0.5% in the coming months.

The ECB President Mario Draghi is confident that recent positive economic data will continue and the euro area economies finally have broad-based traction, driven by improving employment levels and consumer confidence. Although the inflation level has still not reached the 2.0% target, the bank admits that “a very substantial degree of monetary accommodation is still needed for the upward inflation path to materialise”. There is every possibility that the bank could consider the possibility of rate hikes and a tapering of its massive QE monthly purchases as early as next month.

As he had promised in his manifesto, Donald Trump is keen to overhaul the US tax system, including slashing corporation tax from 35% to 20% and doubling the amount individuals/families can deduct (before paying tax) to US$ 24k. There is no doubt that the tax system is cumbersome, complex and out-dated and any simplification would make the country more competitive. It will be interesting to see how some of the country’s big companies, that seem to hide profits in offshore locations, react!

One of the major decisions ever made in Saudi Arabia is that of allowing women to drive in the Kingdom. It is a sign to the rest of the world that it is committed to implementing ambitious economic and social reforms that can only benefit the long term future of the country and the region. To some of the women in the Kingdom, come June 2018, Life Is A Highway.

Posted in Finance | Tagged , , , , , , , , , , , | Leave a comment

I Get Knocked Down But I Get Up Again!

On Sunday, Sheikh Ahmed bin Saeed Al Maktoum launched the operation of 50 Tesla electric cars to be used by Dubai Taxi Corporation’s limousine fleet. This is the first batch of a 200-vehicle order which are fitted with several components for self-driving, in line with RTA’s target of making 25% of all taxi rides driverless by 2030.

The latest hotel in Emaar Hospitality Group’s portfolio will be the 202-key Address Harbour Point. The property is part of the developer’s 1.4 million sq ft twin tower project (of 65 and 53 storeys) in Dubai Creek Harbour that will also include Address Residences Harbour Point, along with a raft of retail and food outlets.

Bin Ghatti Developers already has 30 projects in Dubai which will add 6k residential units to the emirate’s portfolio. Currently, the company is planning a further US$ 817 million investment on 17 new projects in various locations, including Business Bay, Dubai Silicon Oasis and Dubailand.

Invest Group Overseas has forecast that its total investments will reach US$ 1.2 billion by 2020, including a US$ 245 million Dubai residential project due for launch later in the year.

Following the recent initiative by UK-based developer to accept Bitcoins for some units of their Aston Plaza and Residences in Dubai Science Park, fäm Properties has announced that it will accept the crypto currency for property rentals for a limited number of City Walk apartments.

Bloom Education expects that its contemporary institution, focusing on the Arabic language, arts and culture, will open in time for the 2018/2019 academic year. The centre, located in Barsha South, will see prominent Bahraini jeweler and artist, Rayyah Fathalla, as its first director. The 89k sq mt campus will also have two K-12 schools – one teaching the British curriculum and the other International Baccalaureate – and will have 4k students.

The 700 MW fourth phase of the world’s largest single-site concentrated solar power project has been won by a consortium of China’s Shanghai Electric and Saudi Arabia’s ACWA Power. The US$ 3.9 billion award equates to US$ 0.073 per kilowatt hour and the project will be commissioned in stages starting from Q4 2020. It is forecast that the Mohammed bin Rashid Al Maktoum Solar Park will generate 1k MW by 2020 expanding to 5k MW over the following decade.

A report by the Dubai Chamber of Commerce and Industry estimates that spending within the local tourism and travel sector, which accounts for 12.1% of the country’s GDP, will grow from 2016’s total of US$ 43.3 billion to US$ 56.0 billion by 2022. The main drivers behind this impressive growth are Expo 2020 and the numerous mega projects launched over the past year. One of the targets of Expo is to see the number of overseas visitors total 20 million which would be a 34.2% jump from last year’s figure of 14.9 million.

Abraaj Group and France’s Engie have agreed to develop a wind power platform in India, which could generate one gigawatt. This will go a little way to help the country reach its target of 175GW from renewables by 2022, 60GW of which would be from wind power (India already has wind power capacity of 32GW). The Dubai-based private equity firm, which manages over US$ 11 billion in assets, has two other Indian wind energy agreements – a 2015 deal with Aditya Birla Group and this year it became a majority shareholder in Jhimpir Power.

Dubai’s July annual inflation rate of just 1.0% is at its lowest level in over two years. During the month, there were declines in transport prices by 1.7%, whilst food and beverage remained flat but housing increased by 0.9%.

UAE’s new Excise Tax, which will commence on 01 October, will only be collected in e-dirham – the federal government’s e-payment platform, introduced in 2011; the prepaid cards are a means of payment for more than 5k government services. The government has introduced the “sin” tax – which will see a 100% levy on tobacco and energy drinks and  50% on sugary fizzy drinks – to discourage consumption of products that could be harmful to public health and the environment. In addition, it is expected to add an annual US$ 1.9 billion to government coffers.

Following a May directive from the Central Bank, advising financial institutions and advisors to resolve all mis-selling complaints within 90 days, it seems that the authorities are taking action. To date, over 100 complainants have had funds returned to them following the clampdown, with the Central Bank now having its own consumer protection division to deal directly with complaints.

The Central Bank has announced that medium and long term deposits, that make up 26.9% of the total deposits, have jumped 7.0% YTD to US$ 57.2 billion, compared to the same 7-month period in 2016. The main driver seems to be the Central Bank’s move to raise the deposit interest rate earlier in the year.

According to, HE Mubarak Rashid Al Mansouri, the country’s growth this year will be 3.1%, rising four notches to 3.5% in 2018. According to the Central Bank Governor, this has come about – despite low oil prices – from the economic diversification in the UAE.

It is expected that the expected 4.4% hike in the country’s trade next year, with both imports and exports on the increase, will prove a fillip for the logistics, warehousing and handling sectors. One location that looks to see further expansion is Jebel Ali Free Zone, already home to 328 logistics companies from 29 countries.

It is reported that Emaar Properties has obtained a US$ 1.5 billion corporate finance loan from First Abu Dhabi Bank. The company is also planning an IPO covering 30% of its UAE real estate development business in Q4.

As a 49% shareholder, DP World has announced that it would not be renewing its operating contract with PT Terminal Petikemas Surabaya which expires in 2019. The main reason for this withdrawal was that the Indonesian authorities had failed to meet the Dubai operator’s threshold for continued investment. The financial impact will be minimal as the port represents only 2.5 million TEUs (20’ containers) of DP World’s global figure of 85 million.

This week DP World also spent US$ 405 million when acquiring two local related shipping entities – Drydocks World (for US$ 225 million) and Maritime World, the owner of Dubai Maritime City. The former deal is subject to the successful completion of its debt restructuring process and both deals should be finalised by early next year.

Du is to pay a US$ 161 million interim dividend, with shareholders receiving US$ 0.035 per share.

DXB Entertainments has had a tough trading time exemplified by its Q2 results indicating that its losses had increased sevenfold from US$ 11 million to US$ 78 million on the back of a dip in quarterly revenue to US$ 33 million. This week, its major shareholder, Meraas, has given a US$ 67 million subordinated loan to repay certain debts and to fund ongoing operational expenses.

The DFM opened Sunday (17 September), at 3656 and fell 23 points (0.6%) to close the shortened week (because of the Islamic New Year) on Wednesday, 20 September at 3633. Volumes continued on the thin side, with trading of only 86 million shares, valued at US$ 44 million, (cf 108 million shares for US$ 56 million, on Thursday, 14 September). Emaar Properties was flat at US$ 2.40, with Arabtec down a further US$ 0.03 to US$ 0.80.

By Thursday, Brent Crude was US$ 1.94 (3.6%) higher on the week, closing at US$ 56.43, with gold continuing its recent downward trend, dropping a further US$ 38 to US$ 1,295 by 21 September 2017.

A memorandum of understanding was signed last week by Tata Steel and Thyssenkrupp to combine their European operations in a joint venture. The tie-up will see the formation of Europe’s second largest steelmaker with a combined turnover of US$ 18 billion but could result in over 4k retrenchments.

Following a 2005 US$ 7.5 billion leveraged buyout in which the company found itself  so much in debt going private, Toys ‘R’ Us has filed for bankruptcy – another indicator of the demise of  “brick and mortar” stores. The iconic toy retailer, founded in 1948 by Charles Lazarus, has secured a US$ 3 billion finance package as it tries to restructure by closing some stores and focusing more on expanding online business. Already this year, at least twelve major US retailers, including Gymboree, Payless and Perfumania, have filed for Chapter 11 bankruptcy.

Norway’s sovereign wealth fund hit a major milestone this week when it topped US$ 1 trillion on the back of soaring global stock markets and a weaker dollar. It is still some way off Japan’s Government Pension investment Fund’s total of US$ 1.3 trillion. Interestingly, the Chief Executive, Yngve Slyngstad, has indicated that the fund will be cutting the portfolio’s 23 different currencies down to three – US$, GBP and the Euro – and it would not be considering entering any new different asset class such as infrastructure.

In a bid to attract global companies to its state, Wisconsin has approved the country’s largest ever incentive package – a US$ 3 billion subsidy for Foxconn. In return, the Taiwanese manufacturing conglomerate has pledged a US$ 10 billion new LCD panel factory and to employ up to 13k high quality workers. Whether it works remains to be seen but a recent study indicated that even under optimistic projections break even could take 25 years.

Foxconn (in a group with Western Digital, Toshiba’s US-based chip factory partner) is also involved in a bidding war for Toshiba’s memory chip business. Apple and Dell have combined to also try and acquire this lucrative division of the cash-stripped Japanese industrial conglomerate. However, it seems a third consortium, headed by Bain Capital, has been selected by Toshiba as the leading candidate for a deal worth more than US$ 18 billion.

Following hot on the heels of Bell Pottinger and McKinsey, KPMG becomes the third firm to feel the heat from the fall-out of the Gupta family in South Africa. It seems that chairman, Ahmed Jeffery, chief executive, Trevor Hoole, and five senior partners have left the firm because work for the Guptas “fell short of our standards”. KPMG will also donate the US$ 3 million it earned in fees from the family-controlled businesses to charity and refund almost US$ 2 million fee income earned in compiling a controversial report for the country’s tax authority.

There was a major landmark for Portugal’s economy as, after five years, S&P raised its rating from junk status to BBB-, the lowest investment grade mark, with a stable outlook. The agency cited that the country had made “solid progress” since receiving a US$ 93 billion bailout package in 2011. After years of recession, the country is well and truly on the recovery route, with growth of 2.5% expected this year.

The US Q2 current account deficit came in at US$ 123.1 billion – its highest level since 2008 – with the main culprit being a US$ 5.2 billion decline in income receipts from foreigners, mainly government penalties, along with dipping exports and falling income from overseas investments. Despite all the hullabaloo, critics must remember that the current 2.6% deficit amount to GDP is much lower than the 6% levels recorded in 2005. Latest data also show August import prices and export prices both up 0.6%.

Because of a fall in July exports (by 1.1%) and a 0.7% hike in imports, the euro area trade surplus fell US$ 3.7 billion to US$ 22.3 billion. On an annual basis, exports showed a 6.1% rise but imports grew at the faster rate of 8.2%.

Despite all the negative vibes emanating from the doom and gloom merchants, all is not lost for the UK economy. For example, August retail sales were 1.0% higher, month on month, and 2.4% up from a year ago; for the past 52 months, sales have risen. Although inflation reached 2.9% last month whilst wage levels for the three months to July were 0.4% lower in real terms, than the same period in 2016, there has been no brake on consumer spending. Indeed although food sales have remained flat, retail prices in non-food stores (up 3.2% year on year) and non-store retailing (3.3%) are at their highest levels in over 25 years.

Europe’s “3M” leaders – May, Merkel and Macron – all face a rocky weekend ahead. On Friday, Theresa May is set to give her third major speech in Florence on Brexit with the EU27 demanding money, promises on key article 50 points and clarity on the UK’s future trading relationship. The next day sees the Germans go to the polls and although there is little doubt that Angela Merkel will still be Chancellor, for the fourth time, her party seems set to lose ground to the far right. On Sunday, some 75k elected officials will vote in the French Senate elections and it will be interesting to see how many of the 348 seats go to President Emmanuel Macron’s centrist party.

Whatever happens over the next three days, there will be a knock-on effect felt by the continent. For example, this will be felt in the currency market – if all goes well, the euro will move up, any shocks will see it go the other way; sterling has only one way to go. The bourses will show some movement and move in line with the euro. One thing is certain, come Monday, there will only be two of the leaders who can say I Get Knocked Down But I Get Up Again!

Posted in Finance | Tagged , , , , , , , , , , , | Leave a comment

The Last Thing On My Mind

According to the latest Phidar report, Dubai real estate prices and rents are set to fall on the back of six-year low sales of completed properties and increasing vacancy numbers – quoted “at 35%, in preferred communities sampled”. It also concluded that prices and rents have fallen over the past twelve months – villas being 10.2% down (with rents 4.9% off) and apartment prices flat but rents dropping 3.4%. The main drivers behind the dismal news were the oil price, job cuts and a booming supply of properties. (However some others report that new properties have only totalled 13.3k in H1 and 11.9k and 14.9k over the two previous years – hardly enough to swing the supply curve). More worryingly is the belief that Dubai residential market is overvalued “by around 15% to 20%”.

At the start of this week’s Cityscape Global, the Expo 2020 organisers unveiled their impressive legacy plan  – District 2020 will be a two million sq mt mixed use community including 65k sq mt for residential use and 135k sq mt earmarked for commercial use, with both Siemens and Accenture already signed up.  Following the former’s announcement, earlier in the year, that it would establish a global HQ for airports, cargo and ports logistics at the site, Dublin-based Accenture is the second major company set to open a digital hub in District 2020; the professional services company has already been appointed as Expo’s digital services premier partner and systems integrator.

Key features of Expo will be retained with emphasis on culture, education, entertainment, innovation and sustainability. The UAE Pavilion is set to be a museum, whilst the three thematic pavilions (Mobility, Opportunity and Sustainability), will become new cultural facilities and conference/exhibition centres. There is no doubt that the two pillars of their successful 2013 bid will become reality – an Expo that will amaze the world and building a lasting legacy that will offer a new alternative to urban living.

Cityscape Global is an exhibition that is a platform for Dubai developers and, despite Emaar’s absence, the event did not disappoint. There was a raft of new projects announced that will keep the construction sector busy and boost the local economy.

With a 2020 completion date for the 7k-apartment Royal Pearls project, developer Oriental Pearls has announced that 10% of phase 1 (1.6k apartments) has already been completed and is slated for a November 2019 handover. Located in the Meydan Master Development, the project will also include a community centre, surrounded by water, along with the usual accoutrements of retail, dining and leisure space.

MAG Property Development has announced a US$ 600 million community project based on wellness. Located next to Ras Al Khor Flamingo Wildlife Sanctuary, it will feature the world’s largest wellness centre at 120k sq ft. The gated community will also have 550 mt of Dubai Creek waterfront, along with a hotel. Newspaper reports indicate that MAG is also to launch a US$ 1.1 billion gated community in MBR City.

Nakheel has announced a 38-storey luxury beachfront residential project on Palm Jumeirah which will house 250 1-3 bedroom apartments. Details of their other developments were released. Discovery Gardens Pavilion will add a further 350k sq ft of retail space, along with a 350-key hotel, with construction to start in Q2 2018. A second – Jenan Heights – will see a 2.5k home gated community which will be linked to the upcoming 2020 Metro extension. Others include further expansion of the developer’s Jumeirah Park – 174 luxury 4-bedroom villas – and Jumeirah Park Leisure, with an Olympic-size pool and a16k sq ft gym.

Meanwhile Seven Tides will add 1k new apartments on Palm Jumeirah, as it develops SE7EN Residences. The 14-floor tower, located on Palm Jumeirah and adjacent to the developer’s Dukes Dubai Hotel and Apartments, will see studios selling for US$ 197k up to US$ 967k for 3-B/R apartments. The project should be completed within two years.

The first nine Business Bay “water homes” have been anchored in place, with the initial residents being chosen by lucky draw. The Finnish-built villas, on Dubai Canal, form part of Dubai Properties’ US$ 272 million Marasi Business Bay cluster, which will also incorporate an extensive retail and F&B promenade. The government-owned division of Dubai Holding has also launched the first of four “Marasi” towers.

Having already delivered 1.1k units in the first eight months of the year, Damac expects to add a further 1.7k by year-end that would bring its total lifetime delivery to 19.2k, with a further 42.3k in the pipeline. The Dubai-based developer has hinted that it may not launch any new local projects, as it considers that it may be as big as it can get in the UAE; in the region, it has projects in locations such as Amman, Beirut, Malta, Muscat and Riyadh. To expand its market base and revenue – and currently with only one non-regional project, Icon One residential and commercial tower in London – it is looking at other places including Croatia, Montenegro and Toronto.

Azizi Developments launched the second phase, valued at US$ 817 million, of its massive US$ 3.3 billion Azizi Riviera project. The total project, located in Meydan One, comprises 69 mid-rise towers, with 13k residential units and several hotels; phase 2 covers 17 buildings, housing 4k units. The high profile developer has announced that phase 1 had sold out on the first day of Cityscape Global whilst phase 2 was halfway there. It also intimated that it would launch an ‘iconic’ tower later in the year.

Kleindienst Group also released plans for “the world’s first underwater luxury vessel resort”, to be known as “The Floating Venice”. The US$ 681 million project, located off-shore on The World, will comprise 414 cabins over four decks (including one underwater), the world’s first underwater spa, 24 pools and 12 restaurants and will be able to host 3k guests every day. Gondolas will be in use to ferry guests through the canals to their cabins. The developer, who is also behind The Heart of Europe Islands, will also add 400k sq ft of coral for impressive viewing and expects completion by Q4 2020.

Sobha Group has launched phase 2 of its US$ 1.1 billion Hartland Gardenia Villas. Located on Dubai Water Canal in MBR City, the project covers four million sq ft, 60% of which will be green space.

Shuua Capital has unveiled plans for Dubawi – a mixed use hotel and residential tower, with 500 hotel rooms and 500 serviced apartments. The development, located on SZR, near to Business Bay, will be managed by Shuua’s own real estate asset management division.

Likewise, Deyaar Development announced its US$ 272 million South Bay project, located in Business Bay. The 63-storey structure will house 926 units of which 345 will be hotel rooms, 338 residential and 133 serviced apartments.

Danube Properties, with four projects totalling US$ 300 million to be delivered by year-end, will soon launch a new development, probably located in either Arjan or Furjan.

It seems the ongoing legal battles between developer, Five Holdings Ltd, and Viceroy Hotel Management are still some way from settlement. The US$ 1 billion Viceroy Palm Jumeirah Dubai opened in March but by June, the management contract was cancelled and the property’s name changed to FIVE Palm Jumeirah Dubai. Now there are claims and counterclaims involving how the hotel was run and managed with talk of  breach of trust, doctored invoices, fraudulent accounting, self-dealing, unapproved budget overruns etc. Currently, there are three court cases in Dubai and one in Los Angeles.

Union Properties is considering issuing sukuks as it looks at ways to finance its new property development strategy, totalling US$ 2.2 billion, which would require annual funding of US$ 545 million. The developer has signed an agreement with China State Construction Engineering Corp (who will help with finance) to build MotorCity that would include 18k units.

Q2 saw Union Properties post a net loss of US$ 627 million after provisions of US$ 763 million had been made. Now the company has confirmed that the developer’s long-term interests has been best served by the recent asset revaluation. UP is also to establish two new business units – Union Malls and Al Etihad Hotel Management – to further diversify and consolidate their revenue streams.

Saudi group, Alhokair, has opened MENA Plaza Albarsha Dubai. The MENA brand is expected to grow in the region, with the opening of the 90-room property.

In the 18 months to January 2017, there had been 71k property transactions, totalling US$ 41.1 billion, of which the Chinese ranked 8th with 2.2k deals totalling US$ 845 million. Now the DED is to take action to increase China’s participation in the Dubai sector and has appointed locally-based UC Forward with a Chinese partner to ameliorate this strategy.

According to BNC Network, there are currently 7.9k active building projects in the country with a value of US$ 227.8 billion Of this total, 35.7% of the buildings (valued at US$ 121.1 billion) are to be found in Dubai.

There was no surprise to read YouGov’s latest poll that sees the UAE retain its position as the region’s most desirable location for real estate investment – with Dubai being the most popular city for Middle East homeowners and investors.

Dubai Food Park and China’s Ningxia Forward Fund Management Company have signed a US$ 368 million agreement to build a UAE/Chinese Food Industrial cluster over two years. The 4.38 million sq ft project will cover six components, with an estimated 30 new food plants including two Chinese catering companies.

Emirates Healthcare Development Co has announced that it has obtained a US$ 101 million Islamic syndicated loan. The finance will be used by its Dubai-owned private Saudi German Hospital for operation and expansion purposes.

With artificial intelligence slowly inculcating everyday life, one of the first industries to feel the effects is the financial sector; all over the world, bricks and mortars are being replaced by clicks and sorters. Thus it is no surprise to see Mashreq announcing a 10% retrenchment, over the next twelve months, as the digital age takes hold. The chances of talking to a human voice are quickly diminishing and “your call is important to us” will become more prevalent and annoying in the future.

Last Saturday, Dubai Metro celebrated its first eight years in operation during which time, it has carried 1.028 billion passengers, of which 67% travelled the Red Line and the balance of 339 million travelled the Green Line. The system extends 75 km and is considered the world’s longest driverless metro line, as well as having the biggest underground metro station – Union Station, covering 25k sq mt. There will be a 15 km extension to the Red Line from Nakheel Harbour station to accommodate the upcoming Expo 2020 requirements.

It is reported that CVC Capital Partners could be interested its first ME investment, with UAE-based shisha maker Al Fakher Tobacco Trading, Emaar Properties PJSC’s entertainment division and certain education companies reportedly on their radar. The London-based buyout firm, with funds totalling US$ 85 billion, is one of a growing number looking at ME investments; last year, MENA reported a 26% hike, to US$ 28.5 billion, in the value of foreign buyers acquiring “local” assets.

The DFM opened Sunday (10 September), at 3644 and nudged 12 points (0.1%) higher to close on Thursday, 14 September, at 3656. Volumes continued on the thin side, with trading of only 108 million shares, valued at US$ 56 million, (cf 175 million shares for US$ 83 million, on Thursday, 07 September). Emaar Properties was US$ 0.03 higher at US$ 2.40, with Arabtec down a further US$ 0.04 to US$ 0.82.

By Thursday, Brent Crude was US$ 0.79 (1.4%) higher on the week, closing at US$ 54.49, with gold going against its recent upward trend, declining US$ 17 to US$ 1,333 by 14 September 2017.

Troubled Uber is facing three US legal probes, one of which involves an internal programme known as “Hell” that allowed the ride-hailing company to spy on rival Lyft’s drivers; this was reportedly used between 2014-2016 to entice drivers to work for Uber. Another programme – “Greyball” – was allegedly used to deceive regulators about certain of the company’s operations. The third investigation involves the possible payments to corrupt foreign officials. No doubt new CEO, Dara Khosrowshahi, already has his in tray full, with other problems including the appointment of a Global Head of Compliance, following the resignation of the incumbent, Joseph Spiegler, last week.

The Finnish mobile games maker, Ravi, expects to raise up to US$ 1 billion when it goes public on the Helsinki bourse next month. The company behind Angry Birds reported an annual profit of US$ 317 million, 79% of which originated from games and the balance from brand licensing.

John Lewis posted a 53.0% decline in H1 profits to US$ 36 million on the back of increases in higher costs (including pension and restructuring charges) and ‘dampened customer demand’. However, the Group, which includes Waitrose supermarkets, saw revenues 2.3% higher at US$ 6.4 billion, compared to the same period in 2016. Meanwhile Morrisons recorded a 3.0% Q2 hike in sales, whilst pre-tax profits climbed 40% to US$ 269 million.

It has been a good year for Qantas and its Irish chief executive. Having overseen 5k job cuts and the introduction of new routes, the airline has posted annual profits, as at June, of US$1.1 billion. Alan Joyce has seen his remuneration jump to just under US$ 20 million on the back of improved results and the airline’s shares rocketing.

The Head of the UK Financial Conduct Authority is in cuckoo land if he thinks that the 12k SMEs, who were unfairly treated by the RBS’s Global Restructuring Group during the period 2007-2012 would be happy hearing him decide that it would not be in the public interest to publish its full report. Although denied by the bank, it seems that it made matters worse for such customers so as assets could be seized for their benefit (and profits and bonuses). Evidently 92% of ‘viable’ firms, seen by the GRG met with “inappropriate” behaviour, including higher charges and increased interest rates.

In 2013, the Bank of England declared that it would consider raising interest rates once the unemployment level, then at 7.8%, came down to 7.0%. Since then the rate has fallen to a 42-year low of 4.3%. What has the Bank done? Nothing.

The experts were backing the Economics 101 theory that as employment levels rise, there is more competition for jobs which in turn push wage levels higher. One explanation is that the supply of EU cheap labour has kept wages down, backed by a BofE report indicating that a 10% increase in the ratio of migrant to native workers results in wages falling 1.88%. With annual inflation now at 2.9%, and wage growth lagging behind, the problem will not go away. However, as sterling hits a 15-month high of 1.355 to the greenback, there has to be a solid case for an earlier rate hike.

As widely expected, the ECB maintained all three interest rates unchanged – deposit at minus 0.4%, the main refi at zero and the marginal lending facility rate at 0.25%. This is expected to be the status quo at least until the tapering of the net asset purchases which will be kept at the monthly rate of US$ 72.2 billion (until at least December 2017), following the March change from US$ 96.3 billion.

Some will argue that Mario Draghi should ease off a lot quicker, bearing in mind that the ECB has already bought more than US$ 2.4 trillion worth of assets. It seems that Germany is leading the calls for QE to be curtailed especially now that most of the bloc’s countries are showing signs of solid growth. There is concern that ultra-cheap lending costs may see money going to finance marginal investment projects which could be a catalyst for another financial crisis. The ECB Chairman will be praying that this will be The Last Thing On My Mind.

Posted in Finance | Tagged , , , , , , , , , , , | Leave a comment

Welcome To Paradise

Cluttons has estimated that Q2 property prices dropped for the 12th consecutive quarter, with average prices falling 5.8% over the past twelve months and 14.0% over a three-year period. The real estate consultants also estimated that Q2 falls for apartments were at 1.0%, whilst villas fared worse with a 2.2 % decline. In line with others, it sees the market bottoming out and that the Expo 2020 factor will start having more of an impact on the sector in H1 2018 – a little later than most had earlier estimated. Strangely, it also indicated that villa rents could fall by up to 10% this year, with apartments remaining largely unchanged.

Knight Frank has forecast that prime office rents in Dubai are heading north as latest data shows that average rents to the 12 months to June had dipped 4.5%. However, it was noted that rents in the DIFC rose 1.3% in Q2.

Monday sees the opening of the three-day Cityscape Global and with it a raft of realty projects, including a US$ 409 million mixed-use tower on SZR. Further details will be announced at the event but it is known that Shuua Capital will be managing the development. The Dubai-based investment bank already has a US$ 817 million portfolio of real estate in the UAE and Saudi Arabia.

National Bonds Corporation is to launch phase 3 of Casa Flora, located in Motor City Green Community. Sales will occur at Cityscape Global and will comprise both villas and apartments.

Aston Property Ventures has announced  a world’s first, with its US$ 326 million development in Dubai Science Park; 20% of the project’s 750 apartments will be for sale by the use of the bitcoin; it is estimated  that the cost of a studio will be about 30 bitcoins (US$ 169k) and 85 (US$ 389k) for a two-bedroom apartment. The UK developers, the lingerie businesswoman, Michelle Mone, and her partner Doug Barrowman, expect completion by 2020.

Dubai South has launched its Park Lane residential project.

Dubai Municipality has published the first of its projects, as part of the US$ 350 million Hatta Comprehensive Development, encompassing three sectors – economic/services, education and tourism/sports. Part of the plan is to develop the Al Sherpa heritage area to include eight rest houses and pedestrian pathways.

Damac estimates that it has awarded 370 contracts, totalling US$ 954 million, in the first eight months of 2017. About half of this money has been invested in the developer’s massive 55 million sq ft Akoya Oxygen.

Kleindienst is expected to announce a US$ 681 million development next week. The company has developed The Heart of Europe islands, along with underwater Floating Seahorse housing, located on The World Islands, 4 km off Dubai’s mainland.

MAF’s newest hotel, Aloft City Centre Deira, is set to open in Q1 next year. The property, covering some 28.8k sq mt, will have 304 rooms, including 29 suites.

After the local success of its hotel brand, Emaar is set to manage The Address Madivaru Maldives Resort & Spa. Due to open in 2020, the hotel, located some 20 minutes by air from Male Airport, will have 80 beachside and over-water villas, some of which will be for sale.

The builder of Nakheel’s Deira Mall is set to raise finance of US$ 272 million. United Engineering Construction will use the proceeds for the building of this major shopping centre – a project that is estimated to cost US$ 1.7 billion.

UK’s biggest drug maker, GlaxoSmithKline, is planning to build a facility in the UAE next year, in a bid to boost regional sales. The maker of drugs, such as Augmentin and Panafon, will manufacture three, as yet undetermined, drugs in their factory which will probably cost in excess of US$ 100 million. (BMI expects the regional pharma sector to grow by 3.7% to US$ 33.4 billion this year).

The Banker magazine has ranked Dubai as tenth in the world for international financial centres, based on several factors including economic potential, business environment and financial market indicators. The 13-year old Dubai International Financial Centre is recognised as the leading financial hub in the MENA region; last year, the number of incorporated companies rose by 14.0% and by the end of June was home to 1.75k entities.

The RTA has signed an MoU with Siemens to extend its use of 3D printing technology that was first used last year by the rail agency for designing and manufacturing spare parts.

Following the recent decision by Qantas to move its Asian hub from Dubai to Singapore, comes the news that the emirate will become the regional centre for Cathay Pacific. The Hong Kong-based carrier confirmed that Dubai will become its hub for all passenger and cargo operations across the region.

Although ME airlines reported a 4.5% annual increase in passenger traffic in July, this figure is still well down on the five-year 11.2% average. IATA estimates that load factors rose 0.7% to 81.5% but noted that there was a slowdown in the expansion of non-stop services by the larger carriers. The industry has also been hit by regional conflicts, proposed US travel bans and rising costs.

July MENA hotel RevPar (revenue per available room) dropped to a five-year low, to US$ 85, as very weak demand saw hoteliers giving attractive discounts to attract business; occupancy was 1.0% higher at 60.4% but the average room rate dipped 12.7% to US$ 141. The profit per room was at its lowest level for some time at US$ 74 – a figure that was 51.8% down on the annual average.

The Department of Tourism has reported that the first seven months of the year saw tourist numbers 9.5% higher, at 9.2 million. The top three source markets – India (1.1 million), Saudi Arabia (904k) and the UK (712k) – accounted for 29.5% of the total.

The country’s third telecom operator came on line this week. Emirates Integrated Telecommunications Company (who also own du) has launched Virgin Mobile. The new entrant offers a fully digital service and increased choice for the country’s users who can select their own numbers and customise mobile packages.

August’s UAE Purchasing Managers’ Index grew at its fastest pace in over two and a half years, climbing by 1.3 to 57.3, month on month. According to the Emirates NBD’s monthly report, the main drivers behind this boost were impressive growth in new orders, inventories and output. With further investment relating to Expo 2020 due to be announced shortly, the recent economic improvement seems set to continue.

The UAE’s total non-oil trade for Q1 grew by 3.1% to US$ 109 billion – with direct foreign trade accounting for US$ 74 billion (67.8%) and trade from the free zones the balance of USS 35 billion. Both imports and reexports increased by 5.2% to US$ 67 billion and 7.4% to US$ 30 billion; exports totalled US$ 12 billion.  The three leading imports – gold (US$ 9.5 billion), mobile phones (US$ 6.6 billion) and motor vehicles (US$ 4.0 billion) – accounted for 30.0% of the total.

SOUQ.com, recently bought out by Amazon, has acquired the remaining shares in Wing.ae to take a 100% stake in the local online logistics supplier.

The DFM opened Monday (04 September), following the Eid Al Adha holiday, at 3638 and nudged 6 points higher to close on Thursday, 07 September at 3644. Volumes continued on the thin side, with trading of 175 million shares, valued at US$ 83 million, (cf 116 million shares for US$ 59 million, on Wednesday, 30 August). Emaar Properties was US$ 0.05 higher at US$ 2.37, with Arabtec down a further US$ 0.03 to US$ 0.86.

By Thursday, Brent Crude was US$ 1.63 (3.1%) higher on the week, closing at US$ 54.49, with gold continuing its recent upward trend, jumping a further US$ 27 to US$ 1,350 by 07 September 2017. According to Warren Buffet – “gold gets dug out of the ground in Africa, or some place. Then we melt it down, dig another hole, bury it again and pay people to stand around guarding it. It has no utility. Anyone watching from Mars would be scratching their heads”. Nevertheless, investing in such a “useless” metal has been profitable this year – it has risen 17.3% since its 01 January opening of US$ 1,151.

In the past week, VW has had to recall nearly 2.1 million vehicles because of a faulty fuel pump which can cause an engine to stall. 1.8 million vehicles in China were recalled, after an April 2016 investigation by authorities and 281k in the US for similar problems.

The merger between the UK engineering software firm Aveva and the software division of Schneider Electric will result in a new US$ 3.9 billion entity. The French company will be the majority shareholder.

Lego is planning to reduce its workforce by 7.7% to 16.8K on the back of a slowdown in business reflected in H1 falls in both revenue and profit – by 5.0% to US$ 2.3 billion and 3.0% to US$ 686 million. The toymaker indicated that the business had become too complex and needed a “reset”.

A US$ 30 billion deal sees a tie-up of UTC (who make Pratt & Whitney jet engines) and Rockwell Collins, who will combine their aerospace parts businesses, under a new entity, Collins Aerospace. The deal, which will need regulatory approval, is one of the biggest in aviation history and may prove a headache for plane makers, Boeing and Airbus, as they are continually striving to cut costs. Following this shakeup, the new entity will have size and greater negotiating power on its side.

This week, the World Trade Organisation reversed a previous decision to rule that Boeing had received state aid to build new aircraft. This “victory” for the US aircraft manufacturer may be short-lived as Airbus claim that other issues over alleged government support are on the table. This case concerned the state of Washington giving Boeing tax breaks, valued at US$ 9 billion, which effectively shut out imports. However, the 13-year old battle between these two aviation giants is far from over.

Bell Pottinger has been ejected from its trade body, the Public Relations and Communications Association, because of its work in South Africa, for a company owned by the Gupta family, had “incited racial hatred”. Its campaign for Oakbay Capital emphasised the power of white-owned businesses in the country. There are doubts that the firm can continue as more clients will abandon the “sinking ship” in the wake of its PRCA expulsion and negative press; by Thursday, the global firm had appointed BDO to look at options going forward, including a possible sale. (The Guptas have had close ties with President Jacob Zuma who has faced corruption allegations over his ties with them).

With a monthly fall of 0.6 in July to 53.2, the IHS Markit/CIPS PMI slowed to its lowest pace in a year on the back of rising costs for fuel, imports and payroll. It reports that lack of business confidence, mainly because of the uncertainty around Brexit, has led to delays in spending decisions.

Australian exports (up 2.7%) are performing better than expected, driven by higher volumes of LNG and iron ore. Analysts expect quarterly growth could be as high as 1.2% – a lot higher than the initial 0.7% forecast. The Australian dollar is still trading at just under the US$ 0.80 level and there may be concerns that the relatively high AUD may lead to slower economic growth.

The manufacturing sector also grew at a faster rate than expected with the August ISM PMI up by 2.5 to 58.8 – its highest level in over six years. The main driver seems to be in job growth where the index was 4.7 higher at 59.9 which pushed the employment index to 61.3. There is no doubt that business conditions in the US are on the march with backlog, employment, exports, new orders and production all heading north.

Although the 2017 hurricane season is far from over, the last two have caused untold damage and numerous fatalities. Hurricane Harvey has left 50 people dead and 43k homeless, with the Texas Governor Greg Abbott estimating that the reconstruction bill could top US$ 180 billion.

Fast on its heels came Irma that developed near Cape Verde Islands last week and by 05 September had intensified to a Category 5 hurricane. The storm wreaked catastrophic damage on many Caribbean islands – such as Anguilla, Barbuda, Saint Barthélemy, Saint Martin and Virgin Islands – before smashing Cuba and Florida. With 92 deaths already announced and a damage bill that could top that of the 2005 Hurricane Katrina, many regional economies will be in tatters and will take time (and money) to return to normality. Meanwhile many West Indians (and tourists) will be hoping for a speedy return and an early Welcome To Paradise.

Posted in Finance | Tagged , , , , , , , , , , , | Leave a comment

Give Peace A Chance

Reidin-GDP estimate that developers have handed over 13.3k units in H1 (compared to just 8.7 units a year earlier); the consultancy expects the final figure to be in the region of 27k by 31 December 2017 and 31.3k a year later. However, that would be a marked increase on the 2015 and 2016 deliveries of 11.9k and 14.9k. Whatever materialises, there is  no doubt that developers will continue to set the supply/demand curve as close to equilibrium as possible. In an earlier blog, it has been estimated that at current levels of population growth supply would need to be nearer 40k. It is interesting to note that Dubai Silicon Oasis (2.8k units) and Dubailand (2.5k) accounted for nearly 40% of the total YTD handovers and at the higher end of the market Downtown (1.4k) and Business Bay (869). The current occupancy rates for Dubai apartments is 88.4%.

Al Nabooda Construction Group has been appointed by Emaar Properties as the main contractor for its two Creekside18 37-storey towers. The project, located in Dubai Creek Harbour, will comprise housing and commercial units.

Emaar Properties also announced the launch of its Dubai Hills Mall which will serve the residents of MBR City and surrounding environs. To open in H2 2019, the development, covering two million sq ft of gross leasable area, will have 750 outlets including seven anchor stores, a hypermarket and a Cineplex. It will also have parking for 7k vehicles and will be directly linked with the Metro.

Having been awarded a Wasl Asset Management contract to build the first phase of wasl 1 development, Kele Contracting has already started work on the four towers. The work is scheduled for completion by H2 2019 and when all four towers are built, the development will comprise 746 residential units.

Orion Real Estate Development has awarded a US$ 48 million contract to troubled Dubai-based engineering and related services company Drake & Scull subsidiary, GTCC. This is related to MEP (mechanical, electrical and plumbing) work for the developer’s 34-storey West Bay residential tower in Business Bay.

With Cityscape Global 2017 just two weeks away, Nakheel has whetted investors’ appetites by announcing that it will launch five new projects at the three-day mega event. The developer has already intimated that it expects to jump its revenue nearly three and a half times to over US$ 2.0 billion by 2021, along with a portfolio of 36.5k residences, 5k hotel rooms and 17.6k sq ft of retail space.

As Indians accounted for 13.2% (US$ 3.3 billion) of Dubai’s real estate transactions last year, it is no surprise to see Azizi Development open a sales office there. The Dubai-based developer has recently launched its massive US$ 3.3 billion Azizi Riviera project. Located in MBR City Meydan One, it comprises 69 mid-rise towers, which will house 13k residential units, along with three hotels and an integrated retail space.

Damac Properties is considering investment opportunities in Toronto, with the developer’s chairman, Hussain Sajwani (who owns 70% of the company) meeting its mayor, John Tory. The city is one of the fastest growing in the Americas.

Gulf Sotheby’s International has acquired a 51% stake in rival property developer, SPF Realty, for an undisclosed sum. The new entity will result in a doubling in the number of brokers to 100 and the integration of both entities’ client bases.

Since its inception, Dubai Chamber of Commerce’s entrepreneurship development programme, Tejar Dubai, has received 260 business ideas and has launched 28 commercial projects to date. The majority of these entities are involved in smart business, retail and logistics services.

Dubai International continued to break records as July passenger numbers showed a 5.9% hike to 8.1 million – a new monthly high for the world’s largest international airport. Although the number of flights dropped 4.7%, there was a 10.1% boost in the number of passengers per aircraft to 243. It also handled more cargo – at 213k tonnes, 5.0% up on the same month last year.

The Minister of Economy, HE Sultan Al Mansouri, is hoping that the introduction of new legislation will help the country’s productivity that in turn will boost the contribution of the non-oil sector from the current level of 70% to 80% over the next four years. Some of the new laws will cover foreign direct investment, industry regulation, commercial transactions and arbitration, all of which will improve the investment climate, along with business confidence and competitiveness. The Minister expects 2017 non-oil growth at 3.1% rising to 3.7% next year and this follows the 2016 return of 2.7% (and 3.8% for oil growth).

There was a 4.6% annual increase in UAE banks’ assets to US$ 716.6 billion, as deposits rose by 7.1% to US$ 433.8 billion, by the end of last month; over the same period, loans/advances were 3.5% higher at US$ 434.3 billion.

Despite a 9.6% hike in H1 revenue to US$ 2.29 billion, DP World posted a marginal 0.3% fall in profit to US$ 606 million. In line with the continued growth in global trade, the world’s fourth largest terminal operator expects to meet full year market expectations. The company’s cash position has grown 10.5% to US$ 1 billion since 30 June 2016 and has budgeted capex of US$ 1.2 billion for this year; the main areas of expenditure are Jebel Ali, London’s Gateway, Canada’s Prince Rupert and Somaliland’s Berbera. It also reported an 8.2% jump in the number of TEUs (20’ ft equivalent units) to 33.9 million.

Emirates REIT posted a 21.5% increase in H1 rental income to US$ 24 million, with service and other fees 6.8% higher at US$ 3 million. However, the country’s first real estate investment trust recorded a 23.1% slump in profits to US$ 18 million on the back of a fall in revaluation gains compared to the same period a year earlier. Since it announced that it has seen a 6.9% rise in its aggregate portfolio to US$ 772 million, this week it bought the European Business Centre (its tenth commercial property) in DIP for US$ 35 million.

The DFM opened Sunday (20 August) at 3601 and nudged 23 points (0.6%) higher to close on 3624. Volumes declined, closing on Thursday – 24 August – on 177 million shares, valued at US$ 77 million, (cf 234 million shares for US$ 79 million, on Thursday, 17 August). Emaar Properties was US$ 0.02 higher at US$ 2.32, with Arabtec flat at US$ US$ 0.89.

By Thursday, Brent Crude was US$ 1.22 (1.1%) lower for the week, closing at US$ 52.13, with gold down US$ 3 to US$ 1,292 by 24 August 2017.

All is not well in the Uber boardroom, already torn by a legal battle between the former chief executive, Travis Kalanick (who has control of three board seats), and major investor, Benchmark. Still searching for a new CE, COO and CFO, and with Benchmark accusing the co-founder of fraud and intervening with these executive searches, some shareholders are worried that the company is being torn apart and “losing the plot”.

Amazon.com has made progress this week in its attempt to acquire Whole Foods Market for a reported US$ 13.7 billion. If successful, it would give the world’s largest online retailer an entree in the USS 700 billion US grocery market (as well as 465 physical outlets). Although the US chain has only nine UK outlets, the country’s supermarkets were under pressure after Amazon announced that it would cut prices of everyday groceries. No wonder shares in the Big 4 – Asda, Morrisons, Sainsbury’s and Tesco – dipped on the news of the acquisition by a predator that is not too concerned about short-term loss pains for long-term gains and market share.

WPP, the world’s largest advertising group, not only announced its second sales warning of 2017 but also issued a downbeat assessment of the industry. The company has halved its forecast for full year revenue to just 1.0%, as big companies cut their traditional market spends. The result is that advertising agencies have had to slash fees and even offer clients upfront discounts just to retain business. WPP’s Chief Executive, Sir Martin Sorrell, has blamed primarily digital disruption for the slowdown that has seen his company’s shares sink 23.9% to US$ 1,886 since 01 March 2017 (and by 10.9% in one day following Tuesday’s profit warning).

At the end of the week, the vice-chairman and heir to the global mobile phone behemoth, Samsung, was sentenced to five years in prison for corruption. Lee Jae-Yong was found guilty of bribery, perjury and embezzlement and that he had paid US$ 39 million to a close friend of the recently impeached president, Park Guen-Hye, in exchange for business support. The world’s most lucrative tech firm, with Q2 profits of US$ 9.9 billion, also saw two of its executives facing four years in jail for similar offences.

A recent Fidelity study has indicated a massive fall in the value of a typical UK “pension-pot”, compared to a decade earlier. It estimates that in the ten-year period to 2007 – when average annual earnings rose by 3.5% (with 2.5% average inflation rates) – retirees earned an annual income of US$ 15.7k. In 2017, using the average annual data for the previous decade, with 1.7% wage growth and 2.7% inflation, annual income has almost halved to US$ 8.5k.

One of the most improved global economies this year is Japan where most indicators continue their recent upward trend. Its all industry activity index climbed 0.4% in June – and 2.2% on an annual basis – whilst its July Manufacturing PMI reached 52.1. There were noticeable improvements in output, new orders, new export orders, employment, input prices and inventory levels. Q growth levels since 1980 have averaged 0.51% amid a range of minus 4.8% in Q1 2009 to 3.2% (Q2 1990); the latest quarter sees a 1.0% level that could result in the country posting a healthy 4.0% annual growth in 2017.

The Bundesbank now expects the German economy to grow by over 2.0% this year on the back of recently improved data that sees an upturn on the bank’s previous June 1.9% forecast. It also shows the country benefitting from the global economy growing at a stable underlying pace.

New home sales in the US took an unexpected plunge in July, down 9.4%, month on month, to 571k, driven by sharp monthly falls in the North East (down 23.8%) and the West falling 21.3%. However, median house sales, at US$ 314k, were up 0.7% for the month and 6.3% for the year. The same has not happened in the UK, as the August average price of a house dipped 0.9% but still 3.1% higher, year on year.

At this week’s meeting in Jackson Hole, Fed Chair, Janet Yellen, has reminded all and sundry not to rush in and cut the red tape and bank regulations introduced after the GFC. Opponents, including the President, are of the opinion that the system is stifling the economy but Ms Yellen has said that the new environment is “substantially safer” and that the tighter rules are not weighing on growth or lending. It seems likely that the Fed will have a new chairman next February and early indications point to the current Fed vice-chair of financial supervision, Randal Quarles.

There is no doubt that the leaders of both the US and North Korea are rattled. Earlier in the month, President Trump warned the rogue state that it best not to make any more threats to his country or “they will be met with fire and fury like the world has never seen.” Two days later, he tweeted on 11 August that “if anything, maybe that statement wasn’t tough enough” and a day later “Military solutions are now fully in place, locked and loaded, should North Korea act unwisely. Hopefully Kim Jong Un will find another path!” This week sees North Korea protesting at the annual joint US-South Korean military exercises. With bilateral relations sinking to new depths, and the UN yet again full of resolutions but seemingly powerless to act, the last thing the world economy needs is a major political conflict that will derail the recent upturn in global trade and growth. However, it could be too late to yet again Give Peace A Chance.

Posted in Finance | Tagged , , , , , , , , , , , | Leave a comment

Walk On The Wild Side!

There will be another distinct building along the Dubai Canal, with the announcement by RKM Durar Properties of its new twin-tower development – J One. The curved towers (one 19-storey and the other 18), in a ‘U’ shape will house 347 apartments (ranging from studio – 4 B/R), six villas and nine retail outlets. Studio prices start at US$ 225k, with 2 B/R units selling at US$ 600k.

Nakheel has announced that it is mulling over five proposals for the construction of its US$ 245 million Dragon Tower. Located in Dragon City, the twin-tower project encompasses 1.5k residential units and is slated for completion by 2020.

Emaar is planning to build its eleventh tower – 17 Aykon  B Tower – that will house ten luxury residential units. Work will start next year with completion by H2 2020.

Piling work has started on Bloom Properties Jumeirah Village Circle development with completion expected byQ4 2020. The three-building project, Bloom Towers, is set to house 944 residential units, including 689 studio/1 B/R apartments.

Seven Tides, that already owns four hotels in Dubai and one in London, is set to add a fifth to its local portfolio. The property developer is to construct a three tower project in JLT that will include a 4-star hotel, along with two residential buildings. It is also developing one of its ten islands in The World archipelago – a 60-villa luxury resort.

In H1, the emirate’s real estate brokers collected US$ 223 million in commission, according to figures released by the Dubai Land Department. At this rate, the sector is expected to surpass its annual 2016 total of US$ 409 million.

Emirates has renewed its deal with the European Tour until 2021 to be the official airline and to become an official partner of The 2018 Ryder Cup. Under the agreement, the airline will continue to sponsor nine European Tour events, including the DP World Tour Championship,

It is reported that Al Futtaim is in discussions with Marks & Spencer for the purchase and franchising of the retail giant’s business in Macau and Hong Kong. The UK company has had a presence in the former British colony since 1988 and has 27 outlets there.

Flydubai posted a 9.9% increase in H1 revenue to US$ 681 million but saw losses climb 58.5% to US$ 39 million, compared to the same period in 2016. As is the case with most regional airlines, yields are under pressure and margins tightening. The airline has not been helped by on-going regional conflicts and having to cut fares on the back of higher regional capacity. Although fuel costs rose from 23.5% of total costs to 24.8%, it would seem that the airline could return to profitability come the H2 results in February next year.

Norwegian Air is set to start flights from Dubai to Stockholm in October, using the new Boeing 737-Max, with fares as little as US$ 270. The airline, the fastest growing in the world, is looking at other regional routes as it continues its ambitious international expansion. In Europe, it offers one way trips to New York from only US$ 65!

Overseas-AST has been awarded Enoc’s third and final contract for its US$ 1 billion Jebel Ali refinery expansion programme that will result in a 50% capacity increase to 210k bpd. The contract covers the construction of various interconnecting pipelines between the refinery’s processing units, the storage tanks and the berth facilities. The two other contracts were awarded earlier – to Technip Italy for the design and construction of the refinery’s new ancillary units and to Rotary Engineering Fujairah to construct twelve new storage tanks.

Emirates Glass has recently won a number of orders, totalling US$ 27 million, for projects not only locally but also in various countries including Kuwait, Saudi Arabia and other Asian countries. In May, the Dubai Investments’ subsidiary indicated that it would be setting up a new factory in the GCC.

Petrol prices are set to rise again in September with Special 95 retailing 6.7% higher at US$ 0.547, with diesel climbing 5.4% to US$ 0.545 per litre.

The new unified motor policy, with the resulting rate increases in vehicle insurance, and the compulsory introduction of medical insurance are the main drivers behind the H1 growth in the country’s insurance sector impressive H1 results. The total net profit for all 30 listed insurance companies jumped 26.8% to US$ 209 million, whilst gross premiums increased 16.2% to US$ 3.3 billion, compared to H1 2016.

July’s Emirates NBD UAE Purchasing Managers’ Index indicated that the country’s non-oil private sector is holding up well with marked improvements in both output and new work. Despite new export orders falling at a record rate, the index nudged 0.2 higher to 56.0 as inventories rose markedly on the back of future market demand strengthening.

With the Eid Al Hada holiday starting today, 31 August, the local hotels are bracing themselves for an influx of visitors and a four-day bonanza. With occupancy levels set to jump by up to 10%, most hotels will be full to capacity.

On Sunday, the long-awaited VAT legislation was enacted by The President, HH Sheikh Khalifa bin Zayed Al Nayahan. Federal Law No 8 of 2017 will see the introduction of the 5% tax as from 01 January 2018, to be imposed on the buying and selling of most supplies of goods and services at each stage of production and distribution. There will be exceptions that will see certain entities exempted from VAT and others being charged at zero rate.

The DFM opened Sunday (27 August) at 3624 and nudged 14 points (0.4%) higher to close on Wednesday, 30 August, at 3638. Volumes declined closing the shortened week (because of the Eid Al Adha holiday) on 116 million shares, valued at US$ 59 million, (cf 177 million shares for US$ 77 million, on Thursday, 24 August). Emaar Properties was flat at US$ 2.32, with Arabtec down US$ 0.02 to US$ 0.89. For the month of August, Emaar was 3.1% higher at US$ 2.32 (from US$ 2.25), whilst the revamped Arabtec was trading at US$ 0.89 (from US$ 0.94).

By Thursday, Brent Crude was US$ 0.73 (1.4%) higher on the week, closing at US$ 52.86, with gold up US$ 31 to US$ 1,323 by 31 August 2017. Brent started August trading at US$ 52.52 and gained a further US$ 0.34, (0.6%) to close the month at US$ 52.86. Meanwhile, gold raced ahead, gaining 4.3% in August to close at US$ 1,323.

Hurricane Harvey has had a devastating effect on Texas and the Gulf of Mexico with damage estimates to date topping US$ 100 billion, not to mention the human cost, including the loss of some 60 lives. The hurricane also hit the heart of the country’s energy sector resulting in 20% of US oil production cut, refineries closed and major pipelines shut down. The overall impact on the economy could see a 0.5% fall in Q3 GDP growth but this could be offset later when infrastructure repair spending takes hold. In the short-term it would seem that any chance of a rate hike will be put on hold.

Following its June fine of US$ 2.8 billion by the EU courts, Google has submitted proposals of plans to stop favouring its shopping service and to end its anti-competitive behaviour. The US tech conglomerate had been found guilty of abusing its dominance in the EU by giving undue prominence in searches of its own comparison shopping site at the expense of others.

Last year, Wells Fargo admitted that it had created 2.1 million “fake” accounts that had been opened without their customers’ knowledge. Following the revelation, the bank agreed to pay out over US$ 150 million, retrenched 5k lower-level staff and saw the early resignation of the chief executive, John Stumpf. This week it revealed that a further 1.4 million accounts had been created, again without permission, and to add to their woes, the bank is experiencing troubles with its online payment system.

The chief executive of Expedia, Dara Khosrowshahi, has been appointed the new CEO of Uber and has the unenviable task of mending the tarnished image of the car-riding service that has not made a profit over the past seven years. He also has to face disgruntled shareholders, who have witnessed the ongoing boardroom squabbles, and reengage staff whose morale has been sapped by several unsavoury incidents.

There has been a distinct fall in the number and value of mergers and acquisitions in the MENA region, according to a recent EY report. In H1 the number fell 23.2% to 192, allied with an 18.0% decline in value to US$ 31.9 billion. Of this total, the 61 outbound transactions accounted for 61.4% (US$ 19.6 billion) of the total H1 business with the oil & gas sector responsible for US$ 11.5 billion (36.0%). Q2 proved even more disappointing with the number of deals down 40.7% to just 80 whilst the value slumped 36.8% to US$ 12.7 billion, compared to the same period in 2016. The main drag factors include low energy prices and regional conflicts.

With the EPL summer transfer window closing today (31 August), the total spend by the league’s 20 teams is over US$ 1.8 billion (last year US$ 1.5 billion), with US$ 270 million changing hands on the last day, (US$ 200 million in 2016). Two of the bigger transfers were the US$ 97 million Manchester United paid Everton for Romelu Lukaku and the US$ 90 million Real Madrid received from Chelsea for Alvaro Morate. The figure could well have been higher if Liverpool had accepted Barcelona’s offer of US$ 147 million for Phillipe Couthino and Arsenal had sold Alexis Sanchez to Manchester City for US$ 71 million. (These figures pale into insignificance when one considers the US$ 258 million PSG paid for Barcelona’s Neymar and Barcelona’s US$ 175 million for Dortmund’s Ousmane Dembele – a player that, just twelve months ago, was sold to the German club  by Rennes for only US$ 17 million).

The long standing friendship between the Guptas and South African president Jacob Zuma seems to be waning. The family has been accused of using their cordial relations with the president to wield undue influence (and supposed looting of state funds). There is no doubt that the once-dominant family, who moved to South Africa in the 1990s, is becoming increasingly isolated as damming allegations mount and their access to banking facilities dry up. Both parties refute these claims of sweetheart deals.

In Q2, the Indian economy grew at an annual rate of 5.7% (down from 6.1% a year earlier) – its slowest pace in three years. There were marked falls in manufacturing at 1.2% (down from 10.7%) and financial services falling 3.0% to 6.4%. It is obvious that last year’s cash ban and July’s introduction of GST are having a drag effect on growth.

Not before time, the new French President, Emmanuel Macron, has begun the overhaul of the country’s rigid and often archaic labour laws. The main aim of his efforts is to make it easier for companies to hire and fire employees. Currently, the unemployment rate of 9.5% is more than double that of some of its European allies and M Macron wants to reduce this to 7.0% within five years. Bonne chance!

The fact that Theresa May has backed down on her manifesto promise to cut back on fat cats’ remuneration packages comes as no surprise. Her efforts to shake up corporate UK has run into several obstacles and not made any easier by her weakened position, following the recent election and the fact that several large corporations are considering moving head offices to mainland Europe following Brexit. There is no escaping the injustice of the massive variance between the average paid UK worker and some top executives.

Meanwhile the Prime Minister is in Japan on a trip that is focused on bilateral trade post-Brexit. Latest figures, with exports at US$ 13.5 billion higher than imports of US$ 12.4 billion, show that the UK has a trade surplus with the world’s fourth largest economy. Interestingly, Japanese interests own about 1.1k companies in the UK that employ 140k and last year the UK benefitted by inward investment of some US$ 34.8 billion. Naturally, Prime Minister Abe is keen to see the business environment remain basically the same come the UK’s divorce from Europe.

In direct contrast, as the US economy grows at its quickest rate in over two years, on the back of increases in business investment and consumer spending, the UK is heading in the opposite direction. Growth has crawled as consumers spend less with inflation markedly higher than wage growth.

Thirty years following the last time the US tax code was updated, President Trump is trying to coax Congress to act on tax reform – by simplifying regulations and lowering rates. Among the changes he would like to see are a reduction in the federal rate from 35% to 15% and amendments to how firms (probably the likes of Amazon, DHL, Google, Starbucks etc) earn profits overseas. Whether the powerful lobby groups get their way, at the expense of at least some reform, remains to be seen!

Meanwhile the impasse between the US and North Korea is worsening with Tuesday’s news that the rogue state had fired a ballistic missile over Japan. Markets were rattled, with stocks retreating, gold reaching nine-month highs and the greenback softening. This problem is not going away as tensions simmer, with neither side wanting to be the first to blink.

The crisis with North Korea has seen the euro touch US$ 1.20 – its highest level since January 2015. This week’s missile launch over Japan has the markets more jittery and the resulting volatility has seen investors flee the riskier investment assets.

Dubai’s latest tourist attraction has been announced – Sky Walk. Located at the twin tower, The Address Sky View, visitors will be able to navigate the 85 mt long corridor – on the outside – linking the two structures. At 220 mt high, safety harnesses will be mandatory for all who choose to Walk on the Wild Side!

Posted in Finance | Tagged , , , , , , , , , , , | Leave a comment

I’m Still Standing!

Damac launched The Trump Estates Park Residence in Dubai, with the 4-bedrooom villas going on sale on 05 August. This comes a week after the developer launched Golf Vita Residential Towers overlooking the Trump International golf course.

With a third  launch – following its US$ 572 million Polo Residence and US$ 117 million Polo Residences, both in Meydan City – Invest Group Overseas is planning to spend a further US$ 136 million on a new residential tower.

Nakheel confirmed that it had awarded four contracts, valued at US$ 117 million, in relation to its Deira Island waterfront project; they encompass a district cooling plant (US$ 26 million), a sewage treatment facility (US$ 62 million), a substation (US$ 25 million) and piling work (US$ 4 million). Having already awarded a US$ 1.1 billion Deira Mall construction contract to United Engineering Construction in April, the developer has already invested over US$ 2.0 billion in the project.

Troubled Arabtec has won a US$ 99 million contract to build a new mall in Dubai South which will serve a new community with 15k residential units. This will be the focal point of the Emaar South project – a JV between Emaar and Dubai World Trade Centre – which will also include a golf course, hotels, parks, schools and other facilities.

ALEC has won a US$ 163 million contract for Jumeirah Living Marina Gate. Located in Dubai Marina, the tower project, to be completed by Q4 2019, will include 389 private residences, 104 serviced apartments and 15 villas.

Dubai Investments Real Estate Company has secured a local US$ 300 million finance package for its US$ 818 million Mirdif Hills development. The Dubai Investment subsidiary has already started work on the only freehold location in Mirdif, with the mixed-use development being launched in clusters over a period of time.

According to the Dubai Land Department, there was a 16.8% increase in the value of H1 transactions, to US$ 36.0 billion, as the total number rose 25.9% to 35.6k, with Business Bay, Al Barsha South 4 and Jebel Ali the main three contributors; in terms of value, the leading locations were Palm Jumeirah, Business Bay, Burj Khalifa and Dubai Marina. DLD confirmed that in H1, 68 real estate projects were registered, with a total value of US$ 5.7 billion, and that 24 projects, which had initiated in previous years, had been completed. Over the past 18 months, the government agency announced that there had been 95k transactions valued at US$ 106.3 billion.

Core Savills expect that there will be further declines in rents covering Dubai’s freehold clusters but the situation will improve in 2018. However, there will be continued pressure on rents in secondary locations, such as Discovery Gardens and Jumeirah Village, (whilst Dubai Marina and JLT show better rental prospects). The agency also commented that these softer rents have yet to have a noticeable impact on demand but prices have remained sluggish.

The number of visitors to Dubai in H1 reached levels of 8.0 million – an impressive 10.6% increase compared to H1 2016. There was no change, with India, Saudi Arabia and the UK the top three source countries, as Western Europeans accounted for 21% of the total. There were notable increases in numbers from China and Russia – up 55% to 413k and 97% to 233k. The emirate’s hotel room portfolio has increased by 5% to 104k and the 676 establishments posted a 1% rise in occupancy levels to 79%.

Although the output index dipped in July (month on month), there were healthy gains in output and new orders (now at 61.0 and 62.0 respectively) according to the Emirates NBD Dubai Economy Tracker Index which was unchanged at 56.3. The best performing sectors were wholesale/retail (57.9), followed by travel/tourism (56.3) and construction (54.8). Firms still had difficulties passing on rising costs, with margins yet again being squeezed, with the end result of flat employment growth.

Last year, Jebel Ali Free Zone reported a 16.7% expansion in its non-oil foreign trade to 27.9 million tonnes, with a value of US$ 80.2 billion. The three main trading partners, accounting for 28.2% in value, were China (US$ 11.3 billion), Saudi Arabia (US$ 7.0 billion) and Vietnam (US$ 4.3 billion). Machinery, electronics and electrical goods accounted for 49% of the total trade followed by petrochemicals (16%) and food/FMCG (8.0%). On a regional basis, Asia Pacific was the leading location accounting for US$ 32.4 billion (40.4%) of total trade with the Middle East (US$ 27.2 billion) and Europe (US$ 9.9 billion).

H1 saw a 2.4% increase in the number of UAE mobile phone subscribers to 18.7 million. etisalat claimed 10.5 million (a 3.0% increase) and du was 1.2% higher at 8.2 million. It is estimated that mobile phone services account for 80% of the telecoms’ revenue. In H1, total sales reached US$ 8.6 billion with etisalat taking the lion’s share – US$ 6.9 billion (79.8%).

H1 short-term monetary deposits at the UAE Central Bank totalled US$ 119.8 billion, as the June value rose US$ 7.6 billion (6.8%) from the beginning of the year. Such deposits account for 30.1% of the total UAE bank deposits which now stand at US$ 397.8 billion.

Dubai Chamber of Commerce expects that consumer spending in the emirate will grow at an annual compound growth rate of 7.5% and that the total spend will top US$ 261 billion within five years. Accounting for about 45% of the country’s GDP, this is a major economic factor, with the UAE posting the highest consumer spend in the region at US$ 103k. The housing sector, at US$ 75.7 billion, accounts for about 41% of the total, followed by food and transport at US$ 24.8 billion and US$ 16.7 billion respectively.

Al Futtaim Capital has increased its stake in the local fit-out specialist Depa to 26.6%, having recently acquired a further 12.6% for US$ 29 million (77.8 million shares). This makes AFC the largest shareholder, followed by Arabtec, with a 24.0% stake. In June, the company announced the resolution of a long-standing US$ 245 million dispute which had a positive impact on its cash flow.

H1 results were a mixed bag. On the plus side, Emaar Properties posted a 14.4% rise in Q2 profits to US$ 395 million, as revenue increased by 1.9% to US$ 1.0 billion. Meanwhile, Emaar Malls, floated in 2014, posted a 5.0% hike in Q2 profits. It is expected that the developer will have a further IPO towards the end of the year – as it hives off 30% of its development business.

Damac Properties posted a US$ 436 million H1 profit on revenue of US$ 954 million (and booked sales of US$ 1.1 billion); in H1, the developer delivered 3.1k units, including 1.1k in Damac Hills. Its reported gross debt was US$ 1.5 billion, with cash balances totalling US$ 2.3 billion.

Even though its revenue declined by 6.0% to US$ 561 million, Arabtec posted a US$ 11 million Q2 profit (following a US$ 51 million loss in the same period last year). H1 comparative figures show a 2.0% hike in revenue to US$ 1.2 billion and net profit at US$ 16 million – compared to a deficit of US$ 63 million last year. Over H1, the contractor had reduced its share capital by US$ 1.3 billion (to wipe out previous losses) and raised US$ 409 million via a rights issue.

Although still in a loss position, Drake & Scull posted a smaller Q2 loss of US$ 50 million (compared to US$ 57 million a year earlier), including a one-off US$ 19 million impairment charge, as revenue fell 18.0% to US$ 180 million; its accumulated losses stand at US$ 515 million. To clean up its balance sheet, the company is proposing a 75% share write-down (to cancel the accumulated losses) along with a US$ 136 million cash injection by its largest shareholder, Tabarak Investments. It will also sell off non-core assets, including its One Palm investment, and attempt to recover some of its receivables, amounting to US$ 354 million.

Locally listed Gulf Navigation posted a 35.7% hike in H1 profits to US$ 5 million. The result sees the company’s balance sheet improving, now with positive net current assets of US$ 31 million, compared to a US$ 25 million deficit six months earlier. It is still aiming to add a further 20 vessels to its fleet, and boost profits by 300%, over the next four years.

With H1 revenue declining by 4.4% to US$ 113 million, Dubai Refreshments’ profit fell 27.4% to US$ 11 million. The company’s Q2 profit was off 11.9% to US$ 7 million compared to a year earlier. It will be interesting to see the effect of the increase in excise duty has when introduced in October.

Losses at DXB Entertainments grew in Q2 to US$ 78 million from US$ 11 million a year earlier, as both operating expenses (up to US$ 77 million from US$ 14 million) and marketing (up from US$ 2 million to US$ 10 million) moved higher. YTD, the park’s losses have widened from US$ 22 million (H1 – 2016) to US$ 157 million. Despite this, it has invited tenders for the construction of the Six Flags project, covering 3.5 million sq ft, that is expected to cost US$ 708 million.

Dubai Investments recorded a 15.1% decline in Q2 profits to US$ 49 million, with revenue falling 11.0% to US$ 159 million. YTD, profits have fallen by 6.5% to US$ 349 million. Over H1, the company posted a 35.5% hike in revenue to US$ 191 million on the back of strong real estate sector projects which account for 55% of turnover.

Amlak Finance recorded a Q2 US$ 1 million profit, compared to a US$ 10 million loss in the same period of 2016, as impairment costs were reduced and operating costs fell by 30.6%.

Amanat Holdings posted a 10.9% fall in Q1 profits to US$ 3 million, as revenue fell 3.0% to US$ 4 million. However, H1 profits moved higher by 12.8% to US$ 7 million.

Shuaa Capital posted a 147% hike in H1 profits to US$ 10 million – its highest half yearly profit return since the halcyon days of 2009 – as revenue jumped 44.8%. Q2 profits were 124% higher at US$ 3.3 million, as revenue dipped 31.9% to US$ 8.3 million. (This month, it has also acquired 11% of Kuwait-based Amwal International Investment).

Aramex, the Middle East’s largest courier company, saw Q2 revenue 3.6% higher at US$ 311 million but net profit declining 22.8% to US$ 26 million. Two major factors impacted the fall in profit – the Egyptian pound devaluation last  November and a one-off adjustment to its investment in Egypt’s AMC Logistics.

Another local company affected by the fact that the Egyptian currency has fallen by almost a half in the past seven months is MAF. The conglomerate indicated that, if forex rates had remained constant over the period, it would have seen revenue 12% higher and ebitda 9% to the good. It still posted healthy numbers with both revenue and ebitda 4% higher – at US$ 4.3 billion and US$ 545 million. Over the next five years, it expects to double the size of its 21 malls and invest US$ 8.2 billion in the country to open ten new City Centre malls, six hotels, 28 cinemas and 40 Carrefour supermarkets.

The DFM opened Sunday (30 July) at 3606 and nudged slightly higher, moving up 16 points (0.4%) to close the on 3624. Volumes improved closing on Thursday – 17 August – on 234 million shares, valued at US$ 79 million, (cf 98 million shares for US$ 36 million, on Thursday, 27 July). Emaar Properties was US$ 0.02 higher at US$ 2.32, with Arabtec dropping US$ 0.01 to US$ 0.89. For the month of July, Emaar was 6.1% higher at US$ 2.25 whilst the revamped Arabtec was trading at US$ 0.94 (from US$ 0.78).

By Thursday, Brent Crude was US$ 1.22 (2.4%) higher from its 27 July close at US$ 52.71, with gold climbing US$ 35 to US$ 1,295 by 17 August 2017. Brent started July trading at US$ 48.77 but recovered well to close on 31 July, 7.7% higher at US$ 52.52. Meanwhile, gold recorded a 2.2% gain in July to close at US$ 1,268.

Q2 results saw Exxon return a 97% jump in Q2 net income to US$ 3.35 billion which would have been greater if not for Imperial Oil’s loss, caused by problems in its Alberta oil sands operations. Meanwhile, Chevron posted a US$ 1.45 billion quarterly profit – a major improvement on its US$ 1.47 billion deficit over the same period in 2016.

British Airways’ owner, IAG (that also has Iberia and Aer Lingus in its portfolio) posted a 37.0% hike in H1 operating profits to US$ 1.1 billion and, after exceptional items, the profit was still 13.8% up on the same period in 2016. The group experienced a massive IT failure in May that resulted in payments of US$ 76 million to affected customers and it “lost” US$ 52 million because of the fall in sterling. Its CEO, Willie Walsh, expects the good news to continue for the rest of the year, especially as its new budget airline, Level, launched in March, has begun to show early signs of traction.

In July, Chinese house prices, on an annual basis, all increased but July data indicates that the worrying growth of the past few years may be ending, as monthly prices in Beijing fell 0.1%. In July, property investment eased 4.1%, down on the 7.9% posted a month earlier – an indicator that this overheated sector may be cooling; this may dampen even further in the coming months and could reach a 2% level within a year.

Authorities have been trying to clamp down on the shadow banking sector and this will have a knock-on effect on real estate. It is estimated that banks have already used up to 80% of their annual credit quota in the first six months of 2017 and, that being the case, lending growth is bound to soften, with the effect of increasing finance costs. At the end of last year, outstanding yuan loans had jumped 13.5% and this is expected to fall to 12.4% by the end of 2017.

In June, Japan’s industrial production jumped 1.6% – an improvement on the 3.6% contraction recorded a month earlier and on an annual basis was 4.9% higher. Industrial output is expected to continue its upward trend in the coming months. The main drivers in the upturn included chemicals, electrical machinery and transport equipment. Consequently, shipments headed north – 2.3% in June and 5.1%, year on year. Both export prices, up 2.5%, and producer prices – 2.6% higher – expanded on an annual basis. More interesting was the fact that the economy grew by 4.0% in Q2 on an annual basis and the 1.0% quarterly increase meant that the economy has grown over each of the past six quarters.

With a marked improvement in its economy and consumer confidence rising to decade-high of 111.2 in July, the only negative factor in the eurozone continues to be its sluggish inflation level. The June rate of 1.3% is expected to remain at around this level for the rest of the year and is still some way off the ECB’s 2.0% target.  Its President, Mario Draghi, will be reluctant to curtail the bank’s unprecedented stimulus package of the past three years, which currently stands at a monthly level of US$ 70.6 billion, until wage levels shift northwards and catch up with inflation.

A Visa study indicated that July UK consumer spending had declined by 0.2%, month on month and 0.8% over the past twelve months; this resulted in falls over the past three months – its longest period of decline in over four years. The main driver behind this result is the fact that wage levels have not kept up with inflation so that the general public have less to spend and what they buy is becoming more expensive. July witnessed major falls in spending on transport (down 6.1%) and clothing – 5.2% off in the month.

The IMF External Sector Report showed concern that some of the major economies – especially those of the US and the UK – were in continuing external current account deficits, whereas the likes of China and Germany headed in the opposite direction with on-going surpluses. Interestingly, the study concluded that the euro’s valuation was in line with the bloc’s fundamentals but that it was probably too low by some 15%, in relation to Germany’s high current account surplus.

Despite almost dire IMF warnings of its economy heading south, including the fact that it considered the greenback overvalued by as much as 20%, the US continues in positive territory posting a 2.6% Q2 annualised growth hike, driven by increased business expenditure and a boost in consumer spending (which accounts for 67% of the country’s economy). Labour costs in Q2 were 0.5% down from 0.8% in the previous quarter. However, the country’s national debt now tops US$ 20 trillion (of which China and Japan both chip in US$ 1.1 trillion) and most agree that this figure should be reined in by a combination of measures, including improving productivity, boosting savings and passing structural reforms that so far have eluded Donald Trump.

There is no doubt that the last eight months have seen a steep learning curve for the US President but he has defied many who thought he would not even last that long. With the appointment of General John Kelly as Chief of Staff – and the demise of many insiders, including the likes of Bannon (Chief Strategist), Coney (FBI Director), Priebus (Chief Strategist) and Scaramucci (Communications Director) – some sort of normality and stability should return to the White House. After 200 days in office, the Donald Trump can tweet I’m Still Standing!

Posted in Finance | Tagged , , , , , , , , , , , | Leave a comment

Handbags And Gladrags

Propertyfinder reports that Jumeirah Lake Towers is now Dubai’s top performing location for apartment rental values, as it was the only area to show an H1 price increase (1.0%). Other more salubrious sectors, such as Palm Jumeirah, Downtown, Jumeirah Beach Residence and Old Town, witnessed falls of 5.8%, 4.7%, 1.0% and 0.8% respectively. Downtown also recorded the highest decline in apartment prices of 6.7% but still remains the most expensive (at US$ 594 per sq ft), followed by Old Town (US$ 570), Palm Jumeirah (US$ 512) and DIFC (US$ 505).

According to Core Savills, there was a 6% increase in Q2 sales transactions, although the value remained flat, indicating an increasing penchant for more affordable housing. Q2 deliveries of 3.5k units brought the total for the year to 6.6k, with estimates that 2017 could see a maximum of 17.5k new residences. As with most other recent reports, there is a feeling that the market has now definitely bottomed out.

Belhasa Engineering and Contracting Company has been awarded a US$ 163 million contract by Deyaar Development to build 1.2k units in the Afnan and Dania districts in Dubai Production City. 70% of the properties have already been sold off plan and completion is slated for H2 2019.

Following the success of its first two projects, Ellington Properties has launched Belgravia III in Jumeirah Village Triangle. This latest release comprises 224 studio, 1 and 2 bedroom apartments.

Two of Al Ghurair’s hotels – the Rayhaan and Arjaan – are being rebranded under the Swissôtel & Swissôtel Living umbrella, managed by AccorHotels. Both properties – totalling 620 rooms – are located at the Al Ghurair Centre complex, which has just undergone a US$ 490 million expansion.

Tecom has been appointed to develop and operate the US$ 1.4 billion Emirates Towers Business Park, in collaboration with Dubai International Financial Centre, launched by HH Sheikh Mohammed bin Rashid Al Maktoum earlier in July.  Located adjacent to Emirates Tower, the development will include a wide range of high-end office space, three 5-star hotels, along with retail and F&B outlets.

BNC Network estimates that the number of active residential and commercial building projects in the country is 24.4% higher at 7.5k, with a total value of US$ 228 billion. Last month, it was estimated that the value of completed projects totalled US$ 3.0 billion, compared to only US$ 559 million in June 2016. 14.1% of the projects (1.1k) involve buildings of 15 storeys or more, with a value of US$ 100 million (44.0% of the total value).

One of the region’s iconic and oldest fashion retailers is shutting down, just four weeks after opening a flagship store in BurJuman. After thirty years, Sana is to close all 35 of its regional outlets, with the loss of 1k jobs.

A recent On The Go Tours study has noted that, with tourist numbers of 15.3 million compared to a residency of 2.7 million (today – 2.82 million), visitors outnumber the “locals” by 459%. Only two other destinations – Paris at 704% (with 18 million tourists and a local population of 2.2 million) and Kuala Lumpur’s 595% (12 million visitors and a population of 1.7 million) – bettered the emirate in this unusual survey.

Despite the holy month of Ramadan falling in June, Dubai International returned a 3.9% hike in passenger numbers to 6.1 million, bringing the YTD total increased by 6.3% to 43.0 million. The average number of passengers per flight grew 4.8% to 218.

Last month, Dubai-based Premier Composite Technologies was in the headlines for building the “largest ever freestanding carbon-fibre roof” on Apple’s Cupertino headquarters in California. It is also famous for the world’s largest clock – in Saudi Arabia – and now it has received further accolades for building the “largest sliding roof on a mosque in the world”, in Makkah; the 38 mt octagonal-shaped roof was built in Dubai and is now in the Holy City, ready for installation.

Local tech company, Eniverse Technologies, has tied up with San Francisco-based Skycart to bring drone home delivery to Dubai. Operations are expected to start next year and will allow packages of up to 5kg to be sent. Initial operations will start in selected locations, including The Meadows, Jumeirah and Umm Suqeim.

DP World reported a 10.7% increase in Q2 gross container volumes, as it has handled 34.0 million TEUs (twenty foot equivalent units) so far this year. Locally, Jebel Ali has operated 7.7 million TEUs (YTD) – this equates to a 4.3% year on year growth. The expansion figures reflect the improvement in global trade.

Government-owned Dubai Aerospace confirmed that it had obtained financing of US$ 2.3 billion, partly to pay for its recent acquisition of the Irish aircraft leasing company, AWAS; the loan was split in three tranches – US$ 500 million – 4% – due in 2020, US$ 800 million – 4.5% – 2022 and US$ 1 billion – 5% – 2024. With the addition of 263 aircraft from the sale, DA’s fleet will grow to 394 units, valued at US$ 14 billion.

Dubai’s trade recovery can be gleaned from the fact that, notwithstanding challenging global economic conditions, Dubai Chamber of Commerce and Industry reported a 6.1% H1 increase in members’ exports and reexports to US$ 40.0 billion. Saudi Arabia was the emirate’s largest partner accounting for 35.4% of trade, equating to US$ 14.1 billion. It also reported that its membership now totals 210k, following a 10.9%, year on year, hike in numbers.

Although its revenue figures have not been disclosed, Nakheel reported a 21.6% fall in Q2 profit to US$ 316 million, year on year, and an H1 10.5% decline to US$ 719 million. The government developer handed over 870 units in the first six months of the year.

Etisalat posted satisfying UAE results with a 3.0% increase in H1 revenue to US$ 4.2 billion, resulting in a 7.0% hike in profit to US$ 1.1 billion. Group aggregate figures saw revenues at US$ 6.9 billion and profit (before Federal Royalty) of US$ 2.4 billion. In relation to its subscriber base, the UAE’s 12.4 million users account for just 8.9% of its aggregate total of 139 million.

Du posted a 0.3% increase in Q2 profit to US$ 122 million helped by a 1.5% rise in its customer base to 8.2 million users, with revenue 6.2% higher at US$ 837 million. The telco is planning to distribute US$ 161 million as an interim dividend, equal to US$ 0.0354 per share.

The DFM posted a 4.0% rise in H1 profit to US$ 40 million, compared to the same period in 2016, on revenue of US$ 65 million – 5.7% higher; however, Q2 profit dived 19.0%. Trading value for the first six months saw a 1.0% increase to US$ 19.1 billion.

The DFM opened Sunday at 3574 and continued its three-week positive trajectory moving 32 points (0.9%) to close the week on 3606. Volumes nosedived, closing on Thursday, trading 98 million shares, valued at just US$ 36 million, (cf 341 million shares for US$ 124 million, the previous Thursday). Emaar Properties was US$ 0.01 higher at US$ 2.22, with Arabtec failing to gain traction dropping US$ 0.03 to US$ 0.94.

By Thursday, Brent Crude was US$ 3.43 to the good (up 7.1%) at US$ 51.49, with gold climbing US$ 15 to US$ 1,260 by 27 July 2017. Brent should continue to trade in positive territory, helped by the political crisis in Venezuela, lower US stocks and a more stringent approach to maintain agreed quota cuts.

BMW has confirmed that production of its new electric version of the Mini will start in 2019 at their UK Cowley plant.

GM’s Q2 profits declined 14.3% to US$ 2.4 billion driven by lower sales (down 1.0% to US$ 37 billion) and extra restructuring expenses, including a US$ 100 million write-off relating to its Venezuelan facility which was taken over by the Maduro government in April. During the quarter, the car giant sold its European operations to the French PSA Group.

Although Q2 sales were 4.0% higher at US$ 245.5 billion, Nissan posted a 1.1% slip in profits to US$ 1.2 billion, resulting from slowing growth, an increase in raw material prices and forex fluctuations. The car maker expects an improvement in H2.

Despite adding a further US$ 1.3 billion provision (US$ 920 million for PPI claims and US$ 380 million to mortgage holders), Lloyds still posted a 4.0% increase in H1 profits to US$ 3.2 billion. This the 17th time that the bank, which received government bailout funds of US$ 26 million, has had to increase provisions for its previous nefarious activities. Of the big five banks, Lloyds has set aside 60% (US$ 23.4 billion) of their total provisions (US$ 39.0 billion) just for PPI claims. Meanwhile, Barclays returned a Q2 US$ 1.8 billion loss, not helped by that bank having to provide a further US$ 910 million in relation to PPI customer compensation.

Airbus has posted a 17.0% fall in H1 profits to US$ 1.8 billion, as it took an impairment provision against cost overruns on the troubled military A400M and ongoing engine issues with Pratt & Whitney for its A320neo. Q2 figures were even more disappointing as profits fell 27.2%, year on year, to US$ 1.0 billion. Despite all these problems, CEO Tom Enders, still expects to deliver 700 commercial aircraft in 2017 – as long as engine manufacturers meet their commitments. Part of this commitment is delivery of 200 A320neos – to date only 50 have left the factory gates.

It is also reported that it will cut the annual production number of its A380 superjumbo from 28 last year and 15 this year to just eight in 2019. At even current levels, it is highly improbable that the company can return a profit let alone recover some of its US$ 30 billion development costs.

Air France has become the latest international carrier to launch a lower cost airline to compete with the likes of easyJet, Norwegian and Ryan Air (and even Emirates). Joon will start flying medium-haul later in the year, with longer flights scheduled for H2 2018. The French carrier also has a low-cost subsidiary – Transavia. Initially the new company, which is targeting millenials, will use Air France deck crew (who will be on the same pay) but will outsource cabin crew and ground staff.

easyJet has announced that it is expanding its cabin crew by 17.4%, as it takes on a further 1.2k to bring its total to 8.1k; at the same time, it is recruiting a further 450 pilots. The airline has 270 aircraft operating 880 routes in 31 countries and has just applied for a new air operator’s certificate in Austria so it will have no hassles flying in the EU after Brexit is finalised.

Late last year, mining giant Rio Tinto contacted authorities over certain 2011 consultancy payments made in relation to their Simandou iron ore project in the Republic of Guinea. It had earlier sold the mine for about US$ 1.3 billion to Chinese firm Chinalco. This week, the UK’s Serious Fraud Squad has opened an investigation into the matter.

Samsung goes from strength, posting a record 72.7% jump in profits to US$ 12.7 billion, as its DRAM and NAND chip sales tripled to US$ 7.2 billion. The only blot on the landscape for Asia’s third largest company, by market cap, and the global leader in memory chips, TVs and smartphones, is the fact that its Vice Chairman, Jay Y Lee, is in detention on trial for a corruption scandal.

Facebook posted an impressive 71% hike in Q2 profit to US$ 3.9 billion, as revenue rose 45% to US$ 9.3 billion, mostly emanating from advertising; expenses were also up 33% to US$ 4.9 billion. Users topped 2 billion – up 17% year on year.

PayPal returned an 18.3% rise in Q2 revenue to US$ 3.1 billion, as it saw accounts up 80% (6.5 million) compared to a year earlier. As a result, its shares jumped 2.9% to US$ 60.50, with the company upping its annual forecast revenue to US$ 12.8 billion and adjusted earnings per share to top US$ 1.80.

The recent US$ 2.7 billion fine by the EC dented Alphabet’s Q2 profit which, at US$ 3.5 billion, was down by around 40% because of this indiscretion; revenue was 21% higher at US$ 26 billion. Over 87% of the revenue (US$ 22.7 billion) is generated from advertising – including its own sites Gmail and YouTube – and was up 18.0%, year on year.

Following concerns from interested parties to Amazon’s recent US$ 13.7 billion bid for Whole Foods, US regulators will take more time to consider their anti-trust concerns and whether consumer choice would be negatively impacted – or whether they could benefit from lower prices and better delivery.

After two years of haggling, the IMF has agreed to a new conditional bailout that will see heavily indebted Greece receive a further US$ 1.8 billion in bailout funds. The agency’s agreement to this disbursement is contingent on further debt relief from its main creditor – the eurozone – since it estimated that even if the Hellenic nation carried out all of its implementation conditions to the letter, it would be unable to restore debt sustainability; furthermore its debt by 2030 would still be in excess of 150% of GDP! For mainly political reasons, the eurozone countries, especially Germany, with an upcoming September election, has balked at a further “haircut” of Greece’s debt.

There was a marginal 0.3% hike in eurozone government debt to GDP in Q1 to 89.5%, whilst the larger EU28 bloc saw a 0.5% rise to 84.1%. Not surprisingly, Greece topped the table with the highest ratio of debt at 176.2% followed by Italy’s 134.7%, Spain’s 99.4%, France’s 96.0% and Germany’s 68.3%.  (The UK’s debt of US$ 2.280 trillion is equivalent to 87.4%).

The UK’s June budget deficit showed a US$ 2.6 billion year on year jump to US$ 9.0 billion driven by debt increase of repaying index-linked bonds, as interest payments expanded by 32.9% to US$ 6.4 billion, driven by higher inflation. YTD, public sector net borrowing jumped 9.1% to US$ 29.6 billion of which 75% of the total related to the cost of the “day-to-day” activities and the US$ 7.4 billion balance being expended on infrastructure. With government spending increasing by 8.3% but its revenue lagging at 4.6%, it is doubtful that Philip Hammond will meet his annual borrowing target of US$ 75.4 billion.

Apart from Brexit negotiations, the Chancellor has also other problems to face, as the country becomes more belligerent after seven years of austerity.  During that time, the deficit has fallen from 10% of GDP to 2.4% but the casualties have been the public sector workers (apart from MPs themselves), the National Health and the education system. All need much wanted money pumping in and it took this year’s disastrous election result to drive the point home. The problem is that if money is spent on these, there is no chance of a future balancing of books and the distinct possibility of public debt climbing from 87% to triple digits.

The country’s Q2 growth was up by 0.3% (compared to 0.2% the previous quarter) underpinned by output falls in both the construction and manufacturing sectors. One area that fared well, motion picture activities, recorded an 8% increase, thanks to the success of films such as the latest Pirates of the Caribbean and Wonder Woman. Slower growth is expected in the coming quarters, driven by real wages not keeping up with inflation and the Brexit factor. Little wonder then why the IMF cut its 2017 growth forecast from 2.0% to 1.7%, blaming “weaker-than-expected activity”, but maintained next year’s figure of 1.5%.

Although the world body also pegged back US growth forecasts from 2.3% to 2.1%, it maintained a brighter picture of the global economy which saw 2017 and 2018 forecasts unchanged at 3.5% and 3.6%.

To the surprise of nobody, the Fed kept US interest rates on hold, noting that it would be “monitoring inflation developments closely” but would soon be reducing its massive bond holdings. Like many other nations, the world’s biggest economy is worrying economists with a conundrum – the US has seen uninterrupted employment growth since the GFC and a historically low 4.4% unemployment rate but, unlike what is studied in Economics 101, wage growth and inflation have remained stubbornly flat. That being the case, it is difficult to see any rate hike this side of Thanksgiving Day. However, expect an early reduction in its portfolio of investment holdings.

Whether this is the straw that will break the camel’s back remains to be seen but there is no doubt that the country’s stock markets are ready for a major correction. Over the past twelve months, all three major bourses have shown massive appreciation – the Nasdaq by 23.8% to 6382, the Dow Jones 18.3% to 18432 and the S&P 500 by 14.4% to 2482. Investors have already filled their boots and those that stay in at these record levels will surely live to regret their greed (and ignorance).

Famous handbag and shoe maker, Jimmy Choo Plc, has been bought by Michael Kirsten Holdings for US$ 1.2 billion. It is the New York high-end fashion company’s first acquisition since it went public in 2011. Recently it has had its trials and tribulations as it lost its exclusive gloss by expanding its market to outlet malls and discount stores. Now with Jimmy Choo on board and a move away from department stores, the firm may regain some of its former brand image.

The world’s largest luxury goods company saw its H1 profits grow at the fastest rate in seven years. LVMH posted a 23.0% increase in H1 profits (from recurring operations) to US$ 4.23 billion, with revenue above market expectations (Q1 13% to the good and Q2 12% higher). The company is confident that the recovery in the luxury goods sector has been global-wide, having recorded double digit turnover growth in key markets such as China, Europe and Japan. This year, it has seen its share value increase by over 20% to become France’s most valuable company, surpassing Total. A sure sign that it is a good time to invest in Handbags And Gladrags!

Posted in Finance | Tagged , , , , , , , , , , , | Leave a comment

Fool If You Think It’s Over!

A Reidin-GCP report indicated that freehold land prices in the emirate had appreciated by 13% in H1, with this figure to rise even more with Expo 2020 on the horizon. Furthermore, 2016 construction permits are 38% higher than the same period a year earlier; however, there has been a reported 23% slump in Q2 residential transactions. The study also estimated that since 2003, land transactional returns had outperformed Dubai residential units by almost 50%.

Dubai Properties has launched the latest phase of its Remraam community, with prices starting at US$ 122k; located in Dubailand, the 1/2 bedroom apartments will be ready by H2 2019. The master development, launched in 2014, comprises 34 clusters, 64 buildings and 4k apartments with the usual add-ons – community centre, retail, dining and leisure activities.

Jumeirah Golf Estates is set to release land encompassing 700 hectares adjacent to the developer’s current 16 mini residential communities and two championship golf courses – Earth and Fire. The land, which is favourably located within 15 minutes of Expo 2020 site and Dubai World Central, will be made available to all interested developers.

Although there have been adjustments to the design, The Royal Atlantis Resort & Residences is still set to open in 2019. Kerzner International Resorts appointed Six Construct (in a JV with Ssangyong Engineering & Construction) to construct the US$ 1.4 billion, 46-storey hotel that will house 800 guest rooms and 239 serviced apartments.

Reef Mall in Deira will be the location for Dubai’s third “outlet” mall. Brands4u, operated by Concept Brands Group and covering an area of 20k sq mt; it will be a stand-alone, multi-brand outlet and will start with an initial investment of only US$ 4 million for purchasing merchandise.

In a joint statement, Emirates and flydubai confirmed an expansive codeshare agreement that will see both airlines working closer, including “integrated network collaboration with coordinated scheduling”. For both airlines, which will still be separately managed, it is a win-win situation, as the international carrier gets access to a strong regional network, whilst flydubai will have “seamless connectivity to Emirates’ worldwide destinations”. Currently, the combined fleet totals 317 aircraft with 259 wide-body units and 58 new-generation Boeing 737s, serving 216 destinations. There are signs that Emirates could be in the market to add the Boeing 787 Dreamliner (or less likely the Airbus A350) to its fleet and could add up to 100 planes to its current portfolio.

DP World’s subsidiary, P&O Ports, has been awarded a three-year contract to manage the Port de Sete container terminal in south of France, as from October. The agreement, which can be converted to a long-term concession, involves a container yard with a draft up to 14.5mt, a 457 mt quay and an adjacent two hectares of land. Initially, it will act as a feeder service for the eastern Mediterranean but later will see more international activity. The Dubai ports operator has also signed an agreement to advise the Indonesian government on the development of a new port in North Sumatra.

DEWA has awarded a US$ 13 million contract to Dutco Balfour Beatty for the first phase of its new Al Jadaf HQ, known as Al Sheraa. To be ready by the end of 2019, the building is slated to become the tallest, largest, and smartest government net Zero Energy Building in the world; generating 5.8k MWh every year, it will have 16.5k sq mt of photovoltaic solar panels on the roof, producing over 3.5k kW.

The first ever Dubai International Hospitality Week in September will see six events occurring at the same time; they are GulfHost, The Hotel Show, The Leisure Show, The Speciality Food Festival, SEAFEX Middle East, and yummex ME which in the past would have been stand-alone exhibitions. It is expected that the event will see 2k of the top global brands on show, with more than 50k visitors expected.

Beauty products continue to big business in Dubai with the emirate’s trade (imports, exports and reexports) totalling US$ 5.6 billion in 2016; in Q1, reexports have already reached US$ 1.4 billion. The country ranked seventh in the world, with a figure of US$ 239 in per capita spend.

A director of Dubai-based UHY Saxena and Matrix Holdings, Shivani Saxena, has been arrested by Indian authorities in relation to the US$ 560 million AgustaWestland VVIP chopper scam. Following allegations of kickbacks, the Indian government cancelled the contract three years ago and registered a case under PLMA (Prevention of Laundering Money Act), naming former Indian Air Force chief S.P. Tyagi and twenty others.

UK authorities have thanked Dubai Police for their efforts in tracking down tax fugitive Geoffrey Johnson in the emirate; he had been caught travelling on a false passport from Kenya in September 2014, he had been sentenced in absentia to 24 years in jail for his involvement in a complex tax theft involving US$ 285 million and laundering money valued at over US$ 2 billion.

The BRL sector at Dubai Economy reported that in H1, it issued a record number of licences, including 71.8k renewals and 10.5 new applications, of which 73.0% were trade related and 23.4% professional permits.

The IMF’s latest country report has forecast a 1.3% growth this year, on the back of subdued economic performance, slowing global trade and lower oil prices, but a marked improvement to 3.4% in 2018. Inflation eased to 1.8% last year from the previous year’s 4.1%, driven by weaker rents and falling domestic demand. UAE’s overall deficit climbed 0.9% to 4.3% in 2016 whilst the current account surplus was down to 2.4% of GDP (4.7% in 2015).

The Dubai Statistics Centre reported that the emirate’s June inflation level rose 0.86%, month on month, and 2.4%, year on year. The main driver behind last month’s increase was a 7.14% hike in transportation prices whilst food/beverages were only 1.5% higher. On an annual basis, the main factors were increases in miscellaneous goods (11.2%), transportation (5.5%) and education (5.2%).

The country’s bank deposits in June fell 1.7% to US$ 433 billion, month on month, as total assets reduced by 1.2% to US$ 723 billion.

With VAT on the horizon next year, the Ministry of Finance is considering the imposition of corporate taxation; the good news for many is that discussions are still in the very early stages. If implemented, the tax will probably add far more than the US$ 3 billion VAT receipts expected in its first year of operation 2018.

Jumeirah Group, owned by Dubai Holding, will manage its first ever property in Saudi Arabia, the five-star Jabal Omar Jumeirah Makkah Hotel. With views of Masjid al Haram (the Grand Mosque), the four-tower structure will have over 1k rooms and almost 100 villas.

Deyaar Development posted a massive 135% hike in H1 revenue to US$ 86 million, compared to the same period last year, as profit dipped 39.8% to US$ 18 million. However H2 may offer some solace when both the company’s The Atria and Mont Rose developments nearing finalisation.

Government-owned Investment Corporation of Dubai, that includes the likes of Emirates, Emirates Global Aluminium, Emirates NBD, flydubai and Jumeirah in its asset portfolio, posted an unsurprising 13.9% decline in 2016 profits to US$ 4.9 billion, with revenue 0.5% lower at US$ 48.0 billion. The fall was largely attributable to “increased competitive pressure on yields”, especially in the transportation sector which accounts for 55% of ICD’s total turnover but only 18.2% of the group’s US$ 210 billion asset portfolio.

The emirate’s largest lender, Emirates NBD, reported a 5.8% rise in Q2 profit to US$ 550 million. Provisions dipped 0.8% to US$ 169 million as overheads declined 7.3% to US$ 311 million, with impairment charges little changed at US$ 169 million. H1 profit came in 4.9% lower at US$ 101 million.

Its sister bank, Emirates Islamic posted a 282% jump in H1 profits to US$ 105 million although total income dipped 3.0% to US$ 324 million. Dubai Islamic Bank filed a 14.9% jump in H1 revenue to US$ 1.32 billion, as profit rose 7.0% to US$ 583 million, with operating expenses flat at US$ 316 million.

Driven by a 22.3% fall in impairment provisions to US$ 172 million, Mashreq reported a 3.0% increase in H1 profit to US$ 300 million; Q2 profits rose at the slower rate of 2.1% to US$ 152 million. Hampered by a 14.7% fall in commission to US$ 208 million and non-interest income by 9.9%, total operating income fell 5.5% to US$ 817 million.

The DFM opened Sunday at 3537 and, having risen 4.0% the previous week, continued its upward trajectory, moving 37 points (1.0%) to close the week on 3574. Volumes improved, closing on Thursday, trading 341 million shares, valued at US$ 124 million, (cf 279 million shares for US$ 69 million, the previous Thursday). Emaar Properties was US$ 0.05 higher to US$ 2.21, with Arabtec gaining a further US$ 0.01 to US$ 0.97.

By Thursday, Brent Crude was US$ 0.36 lower at US$ 48.06, with gold pushing up US$ 28 to US$ 1,245 by 20 July 2017.

The International Energy Agency expects that oil demand will be higher than expected this year, at 98 million bpd, with increased consumption from Germany, India and the USA; next year, the IEA expects demand to increase by 1.7% to 99.4 million bpd. For oil prices to stabilise or even to move higher, this demand increase will have to be met by strict adherence to quota cuts, so that a reduction in supply will help rebalance the market.

The Footsie is facing a quandary as it hopes to become the lead overseas bourse for the upcoming partial 5% flotation of Saudi  Aramco; overseas exchanges such as New York, Tokyo and Singapore all would like a piece of action that could value the Saudi petroleum giant in excess of US$ 1 trillion! However, to qualify for a London FTSE-100 listing, a company needs a “premium listing” which entails that 25% of shares should be publically tradable in the open market. This week, the UK’s Financial Conduct Authority has launched a consultation to discuss bending the rules to accommodate this lucrative IPO.

Despite a mega influx of funds into its low cost index-tracking iShares, with Q2 turnover 462% higher at US$ 74 billion, BlackRock Inc’s quarterly 6% hike in revenue to US$ 3 billion still disappointed analysts. Although the world’s biggest asset manager, with assets of US$ 5.7 trillion, the US company has faced a barrage of reduced performance fees and other price cuts so as to keep pace with its rivals, as investors move to less expensive products.

Reckitt Benckiser has sold its food business, French’s Food, to McCormick & Company for US$ 4.2 billion; proceeds will be used to  part finance RB’s US$ 16.6 billion recent acquisition of baby formula firm Mead Johnson.

Netflix saw its shares jump 10% on news that it had posted a Q2 profit increase of 60.0% to US$ 66 million, on a 32% hike in revenue to US$ 2.8 billion; it also reported a 5.3% jump in subscribers to 104 million.

The Chinese attraction to acquire overseas trophy assets continues with a consortium, led by Nesta Investment Holdings, offering US$ 11.6 billion for Global Logistic Properties Ltd; the Singaporean company provides warehouse space for the likes of Amazon, DHL, FedEx and Walmart. Following last month’s US$ 13.8 billion buyout of Blackstone Group LP’s European logistics business by China Investment Corporation, this will be the second biggest logistics deal YTD. GLP is also one of the world’s largest real estate fund managers (overseeing assets in excess of US$ 27 billion) and is well positioned to take advantage of the increase in on-line trading.

The price of an average Chinese home has risen 10.2% year on year and 0.7% in the month of June, as the property bubble grows bigger, despite official attempts to deflate the soaring market. If June has anything to go by, this has been a futile attempt as sales more than doubled to 21.4%, month on month, with H1 new construction starts up by 10.6%. Household loans – mostly mortgages – rose 21.0% to US$ 109 billion, month on month.

China surprised the market as it posted a 6.9% annual growth rate in Q2 and this despite the government tightening up on real estate transactions and trying to reduce worryingly high debt levels which would normally have the effect of slowing growth. Other data gives the impression that the economy is on the rebound after growing at its weakest pace since 1990 last year. There were marked improvements in both industrial output (up 7.6% in June) and retail spending – up 11% -along with imports/exports posting higher than expected growth figures of 17.2% and 11.3% respectively.

The Australian dollar has hit two-year highs, as the Central Bank noted that it was upbeat about the local economy and happy with recent improvements in the labour market. On Tuesday, it maintained its cash rate of 1.5% – a level that has remained unchanged since August 2016. However, as the global economy slowly improves, there may be moves for a rate increase by the end of the year.

The impetus of the new French President Emmanuel Macron seems to have had a positive impact on the French economy, as the IMF upgrades its 2017 growth forecast to 1.5%. The world body has been impressed by his “ambitious” reform program which includes a tax overhaul and US$ 5.1 billion of public spending cuts; this should result in a reduction in the country’s debt and budget deficit.

Partly because of an improvement in sterling (and a fall in oil prices), UK’s June inflation rate fell 0.3%, month on month, to 2.6% – its first decline since October 2016. As the rate had escalated since Brexit – and topped the Bank of England’s target of 2.0% – it seemed inevitable the end result would be an increase in interest rates. Although inflation is still outrunning wage growth, the chance of any early rise has been extinguished; however, in the longer term, a marked increase in energy prices and a dip in sterling could see circumstances change.

In August 2015, when its shares were at their lowest point in a year, the government sold a 5.4% stake in RBS which raised US$ 2.7 billion for the taxpayer; nearly two years later, the National Audit Office reported a US$ 2.5 billion loss (as opposed to an expected US$ 1.3 billion deficit at the time). Despite share values falling 8% in the three days before the sale and the fact that details had been leaked prior to the official announcement, the public spending watchdog has the nerve to announce that taxpayers received “value for money” from the sale. The government, which still owns over 70% of a bank that has lost over US$ 75 billion since its 2009 bail-out, now has shares valued at US$ 3.30, which it bought at US$ 6.53! Not many enterprises, perhaps with the exception of the banking sector, would get away with such nonsensical business – and, with more of the same to come, Fool If You Think It’s Over!

Posted in Finance | Tagged , , , , , , , , , , , | Leave a comment

Stuck In A Moment You Can’t Get Out Of

Asteco’s latest report points to declines of 7.0%, on an annual basis, and 2.0%, in Q2, in apartment prices. Rentals nosedived in certain locations, most notably in Business Bay, Downtown, Deira and International City, where falls have ranged between 11%-14% over the past year. Declines in areas such as The Greens and JBR were not as severe, coming in at around 4%. Asteco expects that 17.7k units will be handed over this year – more than double the 2016 figure of 8.8k. (Official figures indicate that in Q1, only 2.6k units, valued at US$ 2.4 billion, were completed).

Chestertons has estimated that Q2 property transactions have declined by 23% and that rents for both villas and apartments have fallen by 2.0%, following a promising start to 2017 in Q1. The firm expects a pick-up in the latter part of the year, with both sales prices and rentals nudging higher.

Meanwhile, in line with most other reports, Bayut.com has concluded that over the past twelve months average property sales prices have declined by 7.0%, whilst there was a larger dip in rentals of 10.4%. However, there was some variance in declines over H1 such as a typical 3-bed villa falling by 7.6%, a 1-bed apartment by 6.1% and a studio by only 0.1%.

Having already awarded a US$ 204 million infrastructure project, Emaar Properties this week invited tenders for the construction of its Dubai Creek Harbour development.

To meet the expanding demands of a growing population, and to enhance the emirate’s position as a regional food hub, Dubai Holding has initiated the US$ 1.5 billion Dubai Food Park in Dubai Wholesale City. The park will act as a central wholesale market and will cover all aspects of the food sector, including infrastructure, logistical and ancillary services; it will also host employee accommodation and will see international and local food companies set up their headquarters. There are estimates that the local food industry, which makes up 11% of the country’s GDP, will grow by 70% to US$ 6.3 billion by 2030.

Monday saw the start of the DSS (Dubai Summer Surprises) 72-hour hour sale that will see up to 75% discounts from over 70 brands, including Calvin Klein, Tommy Hilfiger and Victoria’s Secret. The sale will be a weekly event, until its close on 12 August, and participating venues include Dubai Festival City, Dubai Mall, Mall of the Emirates, Mercato and Oasis Centre.

Following a feasibility study by the US-based Parsons Overseas Limited, it appears that Dubai Municipality’s massive US$ 8.2 billion deep drainage project will go ahead in two stages between 2019-2025. Tenders for the work on two tunnels – Bur Dubai, 62 km long and Deira, 16 km – will be released early next year and on completion, more than 100 pump stations, that currently transfers sewage to treatment plants, will become superfluous. The use of micro tunnel technology eliminates the need for digging up roads.

The RTA has advised that the US$ 110 million Airport Street upgrade, already 45% complete, should be opened by H1 next year. This will improve traffic flow around Dubai International where by 2029, it is expected that by 2020, over 92 million passengers will be using the facility.

A recent Campbell-Hill Aviation Group report has estimated that Emirates supports more than 104k jobs in the USA and contributes US$ 21.3 billion to its economy. On top of that, the much maligned airline (in the US) introduced 580k new travellers to the country in 2015 and generated US$ 3.2 billion of new trade-based revenue. Indirect spending by inbound Emirates passengers added US$ 4.6 billion of new revenues for local businesses and created some 30k jobs. Emirates has 135 flights a week (both passenger and cargo) to the US and serves 14 different locations, often utilising some of its 163 Boeing 777 aircraft (made in the USA).

In a bid to cut costs further, it is reported that Emirates has retrenched a number of senior staff including cabin crew, IT and administration. This follows a hiring freeze last summer but the airline continues to fill “critical roles”. Despite this, the Emirates Group reported an 11.0% hike in employee numbers to 105k in their March annual report.

Gulf Navigation is looking at ambitious expansion plans over the next four years, as it doubles its fleet to 20 vessels, and forecasting a 300% leap in revenue. CEO Khamis Bu Amin is also targeting growth opportunities by opening new facilities in Abu Dhabi and Fujairah, as well as fostering joint ventures. To help with financing, the company is set to issue a US$ 250 million sukuk in Q3.

June’s Emirates NBD Dubai Economy Tracker Index showed a marked 1.5 jump to 56.5 from a month earlier – an indicator that the Dubai economy has expanded at a faster rate in H1 than a year earlier. Although showing the slowest improvement, travel/tourism still posted a credible 54.0, whilst wholesale/retail (at 58.0) and construction (57.4) were the standout performers; however, employment in both sectors continues to disappoint, with the former flat at 50.5 and the latter down from 51.1 to 48.4.

Dubai Customs reported that the emirate’s Q1 non-oil trade was up 2.7% to US$ 89.1 billion – and this despite the headwinds felt by the global economy and trade. The IMF’s latest forecast is for Dubai’s economy to expand 4.0% this year, following a 2.7% increase in 2016, aided by Expo 2020 infrastructure spending.

The delayed US$ 272 million Dubai Safari Park project will open in “the next few months”, according to Dubai Municipality. The project, located in Al Warqaa-5, covers an area of 119 hectares and will be home to 1k animal species, 35% of which are rare and endangered.

Etisalat has terminated its management and technical support agreements with Nigerian firm, EMTS, and will phase out the use of its branding in that country. Etisalat Nigeria, the fourth largest operator in Africa, is 40% owned by Etisalat with the other two shareholders being Abu Dhabi’s Mubadala (45%) and the Nigerian-owned MyaCynth (15%). With both UAE parties pulling out of the company’s board and management, the Nigerian government had to step in to save the telecom from collapse, after US$ 1.2 billion loan discussions had failed.

The next company to list on the Dubai bourse could be Kuwait’s Zima Holding after shareholders approved raising its equity from KWD 10 million to KWD 35 million, as well as listing its shares on foreign stock markets.

The first results of the H1 reporting season saw the Commercial Bank of Dubai report a 31.6% net profit decline to US$ 91 million, as it posted higher impairment provisions figure – up 84.1% to US$ 145 million. However, its operating income jumped 9.9% to US$ 357 million, driven by hikes in non-interest (16.3% to US$ 117 million) and net interest (7.1% to US$ 241 million), whilst operating expenses climbed 7.0% to US$ 122 million.

The DFM opened Sunday at 3401 and jumped 4.0% (136 points) to close the week on 3537. Volumes improved, closing on Thursday, trading 279 million shares, valued at US$ 69 million, (cf 88 million shares for US$ 33 million, the previous Thursday). Emaar Properties was US$ 0.04 higher to US$ 2.16, with Arabtec gaining a further US$ 0.08 to US$ 0.96.

By Thursday, Brent Crude was US$ 0.31 higher at US$ 48.42, with gold lower by US$ 6 to US$ 1,217 by 13 July 2017. Oil prices had plummeted almost 4% on Wednesday on the back of reports that OPEC’s exports had risen and this, after prices had risen over 10% in the previous eight sessions, from a ten-month closing low.

Libya and Nigeria were the only two members of OPEC that were exempted from the quota cuts introduced last November. In the light of the current downward trend in prices, they could well be requested to cap future output to help in the organisation’s attempt to rebalance the market. The two countries have been invited to join a St Petersburg meeting, later in the month, of OPEC and non-OPEC producers. Some argue that the 1.8 million bpd cutback has been offset by these two countries’ increased output, along with a marked rise in US shale production.

It seems that Adnoc (Abu Dhabi National Oil Co) is considering to list its 300 service stations and a network of convenience stores (valued at up to US$ 14 billion) in an IPO that could raise US$ 3 billion on the Abu Dhabi bourse. The conglomerate is looking at selling minority stakes in its service units, as well as seeking international entities to expand operations and boost revenue opportunities.

It is reported that Cosco is to acquire OOIL for US$ 6.3 billion which would then make the Chinese shipping conglomerate the third biggest in the world, with over 400 vessels. The Tung Chee-hwa family owns 69% and will benefit from the fact that the bid values the Hong Kong shipper at 38% higher than its last Friday’s market price.

As it moves away from its traditional way of doing business – selling office software licensing – to cloud computing, Microsoft is to slash its sales force by “thousands” from its current payroll of 121.5k. It is estimated that the tech firm’s annual revenue, from commercial cloud services, will top US$ 15 billion despite strong competition from rivals, Amazon and Google.

A French court has ruled that Google does not have to pay over US$ 1.4 billion in back taxes.  It  found that the internet search firm did not have to pay French tax on profits of its Irish subsidiary, even though 700 of its work force operate out of France. Last year, the company paid just US$ 10 million to the French exchequer.

RBS, still 72% owned by the UK taxpayer following a 2008 US$ 58 billion bailout, has agreed  to a US$ 4.8 billion settlement with the US Federal Housing Finance Authority, in connection with its dubious role in the risky mortgage products scandal. The troubled bank is expected to be hit with a similar penalty levied by the US Department of Justice and had already provided for some US$ 8.6 billion to cover these two cases.

Philip Morris failed in its bid to sue the Australian government over its introduction of the world-first plain-packaging laws, introduced in 2012. The tobacco giant was also ordered to pay the government’s legal fees and could be left with a US$ 40 million bill.

With the sale of its two Hartlepool steel pipe mills to Liberty House Group, Tata Steel Ltd has completed an overhaul of its UK operations that will see the Indian conglomerate concentrate on its Port Talbot strip products supply chain; it has also invested US$ 1.3 million in its 20-inch pipe mill there. The company had already divested itself of  mills in Teeside, a Scunthorpe steelworks, some Scottish operations and part of its specialty steel business.

Having failed to find new investors, UK fashion chain, Store Twenty One, has been forced into liquidation, with the closure of 122 stores and the loss of over 900 jobs. The closure of the chain, owned by the Indian manufacturing group Alok, is the latest of several over the past three years, the most notable being BHS.  Competition from the likes of H&M, Primark, e-commerce and supermarket chains has made trading more difficult and eroded margins to the point of no return.

In order to repay some US$ 3 billion of fines and penalties, Alpargatas is selling its world-famous Havaianas brand for a reported US$ 1.1 billion. The company, which makes 200 million pairs of flip-flops every year, is owned by J&F which has been involved in a series of corruption scandals that seems to be bedevilling Brazil.

Former Brazilian president from 2003-2011, Luiz Inacio Lula da Silva, has been sentenced to nine years following corruption charges. He was found guilty of receiving an apartment for assisting in winning contracts with Petrobras, the state oil company.

With an estimated 1 in 30 of the old £1 coin a fake, it is no wonder that in March, the Bank of England  introduced a new 12-sided coin that will make it harder for counterfeiters to copy. The old round currency will cease to be legal tender on 15 October 2017. To date, the Royal Mint in Wales has issued over one billion coins since the £1 note was withdrawn in 1988.

It is a pity that UK wage growth does not keep up with inflation, with the result that although the country’s unemployment level at 4.5% (1.49 million) is at its lowest level since 1975 and its employment rate of 74.9% (32.0 million) its lowest in 46 years, real terms falls in total earnings continue to disappoint. Inflation at 2.9% has hit 4-year highs, whilst wage growth lags somewhat behind at 1.8%, resulting in adjusted for inflation total pay falling 0.7%. Consequently, it is unlikely to see the Bank of England raising interest rates in the short term.

Following a US$ 17.1 billion current account surplus the previous month, Japan posted a weaker US$ 14.5 billion figure in May, whilst its trade balance fell from a US$ 4.8 billion surplus to a US$ 1.0 billion deficit. May imports were 15.8% higher, year on year, at US$ 510 trillion with exports up by 12.9% at US$ 500 trillion; the country’s adjusted trade balance fell 9.8% to US$ 12.3 trillion. However, export prices were 5.6% lower on the year, but less than half of the 11.9% decline in import prices. The Bank of Japan reported that overall bank lending, at US$ 4.5 trillion, was 3.3% up on the previous year.

German exports reached US$ 123.1 billion dollars in May – up 1.4% year on year and hitting a new record high; the country’s biggest export market was the EU, with trade 11.8% higher. Over the same period, imports increased by 1.2% to US$ 100.0 billion.

The Federal Reserve reported “slight to moderate” June growth in the US economy, as any noticeable increase in inflation, currently at 1.4%, is some way off despite record employment figures. Over the recent past, wage growth has been sluggish with June data showing an increase of less than 0.2% in average hourly earnings. It is expected that the third increase in Fed rates this year may occur but not before September.

Carillion is one of UK’s top two contractors to the Highways Agency and Network Rail and employs 40% of its total 50k workforce in the UK. To say it is facing tough times is an understatement; the news, that 2017 financials would be “below management’s previous expectations”, spooked the markets on Monday with its shares tanking 38%, followed by a further 30% on Tuesday. By Thursday, its share value had fallen 72% in just four days, having opened the week on US$ 2.48 and closing on US$ 0.71. The company has a pension deficit of US$ 1.8 billion and has set aside US$ 1.1 billion in provisions of which 55.6% relates to overseas markets, mainly in Canada and the Middle East; it has also suspended its dividend payout. The company, with a 48k workforce, has already intimated that it will be leaving Egypt, Qatar and Saudi Arabia and it is inevitable that parts of the group will be sold or closed. It seems that Carillion is Stuck In A Moment You Can’t Get Out Of!

Posted in Finance | Tagged , , , , , , , , , , , | Leave a comment